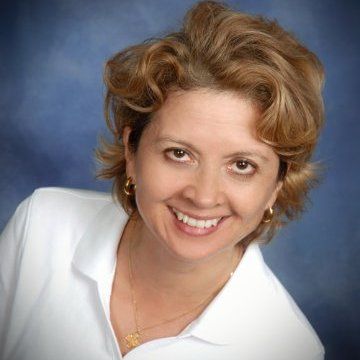
Sylvia Linares-Williams Certified financial Planner™ cfp Professional
Let's make a plan Investment Advisor Representatve
Rollover 401K or IRA
Financial Planner
Generational Planning
Family Love
Let's make a plan Investment Advisor Representatve
Rollover 401K or IRA
Financial Planner
Generational Planning
Family Love


FINANCIAL LITERA
CY How to start. Input form to start a financial Pla
! hour every 2ne Saturday
Start an interest bearing account
Make your 401k into your self directed IRA Rollover
2025 South Lakemont Avenue Suite 100 Orlando Florida
Questions for a CFP?
Changing job
2 things you can do with your company savings plan
Do not leave plan with your old employer.
Rollover to your own self directed IRA. or Roth IRA
Do not convert your old plan to your new employer 401K.

Do you need a will or a trust? What is needed to start to
desi customized plans that can help you achieve a careful balance of control and flexibility, shaping your family's future while responding to its changing needs. We can assist you with:
What Estate Planning Documents Do I Need and Why?
Many people assume having a will is sufficient, but estate planning is more than just preparing a will. An estate plan typically should, at a minimum, include both financial and health care powers of attorney, a Health Insurance Portability and Accountability Act of 1996 (HIPAA) waiver, and living will. While a will can provide for the disposition of your assets upon your death, it is not legally effective to deal with a variety of other situations that could arise during your lifetime, such as incapacity and the need for someone to make medical or legal decisions on your behalf.
In keeping with a goals-based approach, estate planning should incorporate an integrated approach to determine which documents may be necessary to accomplish your objectives.
The documents you may want to consider including in your plan are set out below.
A Will
A will is a legal document that allows you to direct the distribution of your property following your death. Without a will your state’s intestacy statute will dictate who receives your property (which may not reflect how you want your assets to be distributed). For example, do you want a child to receive a large sum of money at age 18? What if you have a child or a spouse with special needs? Do you want an estranged family member with whom you have no relationship to receive assets that you have earmarked for a child or other beneficiaries?
In addition, a will gives you the ability to appoint a guardian for your minor children. Although the ultimate decision as to the appointment of a guardian rests with the appropriate court, by appointing a guardian in your will, you provide the judge with your preferences and may minimize the possibility of family conflict over who should care for your children. When choosing a guardian, you may want to consider not only those willing and qualified to take the job, but individuals who share your values and way of life.
Further, a will allows you to appoint an executor to oversee the distribution of your assets — the person who will be charged with carrying out your wishes when you are not here to do so yourself. You may want to keep in mind that acting as an executor is not an honor; rather, it is a job which requires completion of critical duties. Before you choose an executor (also known as a personal representative), you may want to weigh not only the qualifications of the individual but whether they have the time to devote to the numerous legal and tax duties required of the position. For many, appointing an individual as personal representative together with an institution can provide the right balance of technical experience and familial context.
Financial Power of Attorney
If you own any assets or property in your own name, you may wish to create a financial power of attorney. When you own an asset in your own name (for example, real estate, a bank account, or an investment account), only you have authority over this asset. If you are unable to make decisions regarding your assets, you may need to delegate authority to someone else to handle those assets should the need arise.
A financial power of attorney appoints an individual, commonly referred to as your “agent,” to handle your financial affairs should you become incapacitated or unable to handle day-to-day decision making.
Your agent will be able to act on your behalf by paying your bills, making investment decisions, handling tax and real estate matters, depositing money, and transacting other personal business you would otherwise have handled yourself. Without such a document, it may be necessary for a court to appoint someone on your behalf to handle these matters. Generally speaking, many people would prefer to choose who will make these decisions for them should the need arise rather than having a court make that choice. A financial power of attorney gives you that ability.
When Your Children Become Adults
Once a child attains the age of 18, the child is an adult and a parent can no longer access their medical records or make medical decisions on their behalf without special legal documents. A health care power of attorney naming someone (presumably the parent(s)) as a child’s medical agent will give the named individual(s) the ability to make medical decisions on behalf of the child should the child be unable to do so for themselves. Think about how it would be if you, as a parent, were not able to give or refuse consent for treatment or be able to gain access to medical information.
A HIPAA authorization is another “must have” document for college-aged children. A form signed by your child will permit you to receive information from health care providers about the child’s health and treatment.
Health Care Power of Attorney
Much like a financial power of attorney, a health care power of attorney allows you to designate someone (your agent) to make medical decisions for you should you be unable to make them for yourself.
If you are over the age of 18 and do not have a health care power of attorney, if you are incapacitated a petition will need to be filed with the appropriate court and a judge will appoint a guardian to make you health care decisions. Potentially, this could lead to unnecessary cost and delay which may be avoidable with the correct documents. Again, would you prefer a stranger to make these decisions, or would you rather determine who will have this ability.
A Living Will
If you are over 18 years of age, you may want to create a living will. A living will, also known as an advance health care directive, allows you to specify what end-of-life treatment you do or do not want to receive if you become terminally ill or permanently unconscious and will not survive without the administration of life support. A living will takes the decision to remove life support out of the hands of family members during a very emotional time by stating your wishes in advance.
HIPAA Waiver
If you are over the age of 18, you may want a HIPAA Waiver. While your health care power of attorney and advance health care directive will likely contain language that allows your agent to access your medical records, it is not uncommon for medical facilities to refuse access to medical information without a stand-alone HIPAA waiver. This back up document allows your family members to have access to your medical information so they can speak freely with your health care providers in case of a medical emergency or your incapacity.
If I Already Have Estate Planning Documents, Do I Need to Do Anything?
Your estate planning documents may be the most important documents you will ever write. Often though, after being executed, they are put away for safekeeping and not looked at again. That can be a mistake. You may want to review your plan regularly as your life evolves to determine if your documents still accurately reflect your goals. For example, consider the following common, but important, reasons for contemplating updates to your existing documents:
Next Steps – Create your ICE Pack (In Case of Emergency)
Remember, even the most carefully drafted documents will be of no value if your loved ones do not know where they are located. Consider creating the following, in case an emergency arises.
1. A folder containing copies of your estate planning documents, which someone knows how to find.
2. A special envelope containing your health care documents that is easily accessible should you need to be hospitalized. You may also want to have a copy of your Health Care Directive/Living Will on file with your personal physician and local hospital.
3. Lists of important information for your loved ones to easily access:
· Relevant personal contacts who should be notified in the case of an emergency.
· Assets, debts, expenses, account information, health care and life insurance documentation, as well as other important information should your designated agent, under either a financial or health care power of attorney, need to act on your behalf.
· Online accounts and their usernames/ passwords so that electronically stored photos, videos, email and social media accounts, as well as online accounts with various financial institutions, can be accessed.
· Medical history, medications, and health issues for your health care power of attorney agent(s). Also, do not overlook the importance of having a conversation with your designated agent regarding your wishes.
Finally, do the individuals named in your documents know you have chosen them to serve in a fiduciary capacity? Before you name someone to take on any of these responsibilities, it is important to discuss this with them beforehand.
Conclusion
In these uncertain times, being proactive by putting appropriate and up-to-date estate planning documents in place can help alleviate stress and create a measure of certainty and peace of mind that will serve you and your family well in the years to come. Your PNC Private Bank® team is here and ready to work with you and your advisors.
When to Review Your Will – Checklist
In addition to regularly reviewing your will and estate planning documents every three to five years, you should also consider reviewing your estate plan when these situations and life events arise:
· Upon birth or adoption of a child, grandchild, or other family member
· Following a marriage or divorce
· When someone named in your will passes away
· When a child or grandchild needs educational funding
· When children, grandchildren, or other heirs reach adulthood
· Upon changes in your executor’s, guardian’s, and/or trustee’s circumstances
· When the value of your estate significantly increases or decreases
· The acquisition or disposition of a significant asset
· Upon starting a business or when contemplating the transfer of a business
· Following changes in tax laws
· When you are approaching age 72 (the age when you are required to begin taking distributions from your individual retirement account, 401(k), or other qualified plan)
· After a move to a different state
· If you are diagnosed with a chronic or terminal illness or disability
Planning Using Powers of Appointment
Through the years, the dynamics of your family will change. Your family may grow, children and grandchildren may be born, some offspring may mature into wise adults and some may not, some family members may suffer through illness (perhaps debilitating), and, at some point, every member of the family will die. Of course, changes come from outside of your family, too. Tax and property laws change from one Congress to the next. Unanticipated events occur in the economy or in the financial markets. Businesses may succeed wildly or fail spectacularly.
Given the inevitable changes over the course of a lifetime, you may ask:
· Can I create an estate plan that may be later adjusted for the inevitable changes of life?
· If I plan for today’s circumstances, is it possible to also plan for an uncertain future – even for events that occur after I have departed this life when my estate plan becomes irrevocable?
· Can I plan now to protect my family’s wealth for generations to come, while allowing the plan to take into consideration changed circumstances?
The answer to each of the foregoing questions is yes.
Indeed, it is possible to secure your wealth for future generations yet provide for an uncertain future, no matter what comes, by building flexibility into the plan documents.
While there are many ways to build flexibility into the irrevocable documents that create your plan, using a power of appointment makes your plan flexible by allowing future generations to adapt it to later circumstances.
What is a Power of Appointment?
An important part of any wealth plan is the transfer of wealth from members of senior generations to members of junior generations. Of course, your plan can give property outright to any person. However, doing so fails to protect that property from many risks. Property owned by an individual outright may be disposed of in any manner by such person. Property transferred outright is “unprotected” because it is subject to the claims of the owner’s creditors (possibly including those of a divorcing spouse), it may be invested imprudently and lost and it can be given away, including to persons outside your family. To protect your wealth from those and other circumstances, instead of giving your wealth to your beneficiaries outright, you could create trusts for their benefit. In fact, to protect your property for long periods of time, you can create trusts that last for (and benefit) many generations of your descendants. (Note that some states have laws that require trusts to end by a certain date.[1] Check with your attorney to see how the laws of your state could impact your plan.)
Irrevocable trusts for your beneficiaries are generally governed by the terms that you set when you create the trust. As trust law has developed, however, many states have adopted laws that allow irrevocable trusts to be changed. These laws include judicial modifications (when a court changes a trust), non-judicial settlements (when the beneficiaries and trustees agree to change the terms of a trust) and decanting (when the trustee exercises a power in its discretion to distribute the trust to another trust). Additionally, the terms of your trust can give your beneficiaries the ability to change the terms of the trust by conferring upon them a power of appointment.
A “power of appointment” is a right that the creator of a trust[2] (the donor) confers upon another person (the donee or power holder) to direct the disposition of specified property. The donor of the power of appointment sets the terms as to how the power can be exercised and the steps that the holder of the power must follow to exercise the power. If the power holder does not comply with the requirements of the power of appointment, its exercise could be void.
For example, a power of appointment may:
· be exercisable immediately, or at some time in the future (such as when its holder dies);
· restrict who may receive property when the power is exercised (such as limiting recipients to the donor’s descendants);
· set conditions on what the beneficiaries receive and how they receive it, such as requiring the power to be exercised to create another trust (and not transfer property outright); or
· restrict the mechanism for exercising the power (for example, by only allowing it to be exercised by the power holder’s will and by specific reference to the document creating the power of appointment).
Types of Powers of Appointment
Powers of appointment can be customized to suit your circumstances as well as those of your family.
However, for federal gift and estate tax (collectively, transfer tax) purposes, there are two types of powers of appointment:[3] a general power of appointment and a limited power of appointment.
· A general power of appointment allows the power holder to direct property to be distributed to any person or entity and subject to any condition as specified in the power of appointment, but the power holder must also have the ability to direct the property to be distributed to any of (i) the power holder, (ii) the power holder’s creditors, (iii) the power holder’s estate or (iv) the creditors of the power holder’s estate.[4]
· A limited power of appointment (also known as a special power of appointment) allows the power holder to direct the property to be distributed to any person or entity and subject to any condition as specified in the power of appointment other than (i) the power holder, (ii) the power holder’s creditors, (iii) the power holder’s estate or (iv) the creditors of the power holder’s estate. A limited power of appointment can be quite broad, as it can be drafted to allow the power holder to appoint the property subject to the power to anyone or any entity in the world other than the four above stated exceptions.
Ownership and Powers of Appointment
With limited exceptions, state law creates and governs interests in property and ownership rights.[5] The power holder must look to state law to determine what is owned and the rights conferred by such ownership. For example, a presently exercisable general power of appointment in favor of the power holder allows the power holder to “take” the property subject to the power of appointment. Such a power is the legal equivalent of ownership and subjects the property subject to the power of appointment to the claims of the power holder’s creditors. However, a general power of appointment exercisable by will may not be subject to the claims of the power holder’s creditors during life but could be subject to the power holder’s creditors at death. Conversely, a limited power of appointment (whether exercisable during life or at death) does not confer any economic benefit on the power holder and is not subject to the claims of the power holder’s creditors.[6] As the law of each state is different, you should consult with your attorney to determine ownership rights.
Tax Treatment of Powers of Appointment
Powers of appointment can have important tax consequences to the power holder. Generally, if the power holder dies holding a general power of appointment created after October 21, 1942 (whether the power of appointment is exercised or not), the value of the property subject to the power will be included in the power holder’s gross estate and potentially subject to federal estate tax.[7] The value of the property subject to a general power of appointment would also be included in the power holder’s gross estate if the power holder released or exercised the power under circumstances such that, had the power holder owned and transferred the property subject to the power of appointment, the property would be includible in the deceased power holder’s gross estate under certain other sections of the Internal Revenue Code (IRC).[8]
On the other hand, the value of property subject to a limited power of appointment will not be included in the power holder’s gross estate at death unless the power holder exercises the original power of appointment to
· create a second power of appointment, and
· the second power of appointment can be exercised to prevent the property subject to the second power from being owned outright or being transferred, and
· the period of time during which the property cannot be owned outright or transferred does not reference the date the original power was created.[9]
For gift tax purposes, the exercise or release of a general power of appointment created after October 21, 1942, will be deemed a transfer of property by the power holder and potentially subject to gift tax, unless the value of the property subject to the power that lapses or is released is less than the greater of $5,000 or 5% of the total value of the property subject to the power of appointment.[10]
For income tax purposes:
· to the extent property is included in the gross estate of the power holder, its tax cost basis will become its fair market value at death. The basis of appreciated property will “step up” to its then-fair market value, whereas the basis of depreciated property will be “stepped down.”
· in some cases a trust beneficiary who holds a presently exercisable power of appointment allowing the beneficiary to take the property in a trust (or who had such a power that has lapsed but has certain rights over the trust) can be treated as owning the property in the trust for income tax purposes (making the trust a so-called grantor trust).[11]
Using Powers of Appointment
As circumstances change, powers of appointment can provide flexibility to your plan. There are many ways to use powers of appointment to the advantage of your family. Following are some examples.
As circumstances change, powers of appointment can provide flexibility to your plan. There are many ways to use powers of appointment to the advantage of your family.
Unexpected Problems Arise After Death
Planning for Changed Circumstances
Spouse 1 dies, leaving a trust for the benefit of Spouse 2. The trust requires that its income be paid to Spouse 2 at least annually for life and gives the trustee the discretion to distribute principal to Spouse 2. Spouse 2 also is granted a limited power of appointment to direct the trust property to be distributed outright or in further trust for any of the Spouse 1’s descendants at Spouse 2’s death. If the power is not exercised, the assets remaining in the trust will be distributed outright to the descendants of Spouse 1, per stirpes. Assume that Spouse 1 has two children. Further assume that the oldest child of Spouse 1 develops a substance abuse problem after Spouse 1 died.
Upon Spouse 2’s death, if nothing is done, each of the children would receive one-half of the trust property, outright. In that case, property received by the older child could perpetuate, or even exacerbate, the substance abuse issues. Instead, Spouse 2 could exercise the power of appointment, requiring the oldest child’s share to be held in a trust, to provide for that child (even to the point of paying for treatment). The oldest child’s share would be protected from that child’s potential improvidence, shielded from that child’s creditors and available to care for that child. Moreover, the property would be unavailable to feed that child’s self-destructive behavior.
Special Needs
Using the same facts as outlined above, assume that after Spouse 1 died, the younger child has a child (grandchild) with severe disabilities who will require professional care for life. If the grandchild were to receive property from the trust, such a distribution could disqualify the grandchild from receiving public assistance. Ignoring tax consequences for the moment, assume Spouse 2 and the younger child plan together that Spouse 2 should provide some funds to care for the grandchild upon Spouse 2’s death. In that case, Spouse 2 could exercise the power of appointment in such a way as to provide a trust that could be used in part for the younger child and in part to provide the grandchild with services and items not provided by government assistance. Further, the power could be exercised so that upon the younger child’s death, whatever property remained in the child’s trust would continue in a trust to provide the grandchild with services and items not provided by government assistance for the rest of grandchild’s life. Upon the grandchild’s subsequent death, if there is property remaining in the trust, the exercise of the power would specify which of the descendants of Spouse 1 would receive the property and the conditions upon which it would be received. For example, if the younger child had no other descendants, any remaining property could be added to the trust for the older child.
Financial Windfall
Assume the same facts as outlined above, except that the younger child has children (grandchildren), none of whom have special needs. Further assume that the younger child was a business owner who sold the business for hundreds of millions of dollars. If Spouse 2 takes no action, upon the death of Spouse 2 one-half of the trust would be paid outright to the younger child. This would augment younger child’s estate, which (based on current law) would be subject to a substantial estate tax. Ignoring taxes for the moment, because the younger child already has a large estate, perhaps Spouse 2 could exercise the power of appointment to create trusts for the grandchildren.
Limitations on Exercise
In each of the foregoing examples, because the power of appointment restricted the possible appointees to the descendants of Spouse 1, Spouse 2 could not have directed the trust to be distributed to anyone or any entity other than a descendant of Spouse 1. If the power of appointment had allowed trust assets to be distributed “to any person or entity other than Spouse 2, Spouse 2’s creditors, Spouse 2’s estate or the creditors of Spouse 2’s estate,” Spouse 2 could have directed the entire trust to be distributed to any person or entity (either outright or in trust) other than the four entities prohibited from receiving property. In that case, even though that power of appointment would still have been a limited power of appointment, the group of potential appointees would have been so broad that Spouse 2 could have caused the property to be distributed to virtually anyone, including a new spouse, the new spouse’s children or a charitable organization. Thus, great care should be taken when drafting powers of appointment to balance flexibility with the desire to keep wealth within the family.
Tax Planning with Powers of Appointment
Taxpayers create extensive plans to minimize their overall tax liabilities. As one of America’s great jurists once wrote: “Any one (sic) may so arrange his affairs that his taxes shall be as low as possible; he is not bound to choose that pattern which will best pay the Treasury; there is not even a patriotic duty to increase one’s taxes.”[12]
For decades, taxpayers have used trusts to minimize the amount of transfer taxes required to be paid by each generation of their families. Many of these strategies involve long-term trusts.
These trusts are designed to last for many generations, without being subject to transfer taxes. (Although beyond the scope of this article, usually the transferor has allocated exemption from the generation-skipping transfer tax to the trust so that it has an inclusion ratio of zero, or the trust was irrevocable before September 25, 1985.) This means that the terms of the trusts are crafted so that the value of the trust’s property is not included in the gross estate of any beneficiary who dies. The benefit of avoiding estate tax at each generation is illustrated by the table on page 5.
However, avoiding transfer taxes by holding property in a long-term trust may cause an income tax issue. As the assets in the trust appreciate, the unrealized capital gain in the assets grows. Because the assets of the trust are not considered to be transferred by the trust’s beneficiaries, the assets in the trust never receive a so-called basis step up as each beneficiary dies.[13]
In 2022, each citizen and resident of the United States has an exclusion from the federal estate tax of $12.06 million. This exclusion amount represents a significant increase from exclusion amounts of previous years. In fact, as late as 2002, the exclusion amount was only $1 million. As estate tax exclusion amounts have grown, fewer taxpayers have been subject to the federal estate tax.
Is it possible to both avoid transfer taxes and get a step-up in basis to reduce capital gain tax? To some extent, the answer is yes.
When creating a new estate plan, you could create trusts that optimize both transfer tax and capital gains tax savings. To do so, the terms of your trust could grant its beneficiaries a carefully crafted general power of appointment. Each beneficiary would have a general power of appointment (exercisable when the beneficiary dies) over an amount of property in the trust determined by a formula. The formula would limit the amount of property subject to the power of appointment to the beneficiary’s available (or unused) estate tax exclusion amount (so that no estate tax would be paid). Further, the formula would apply to those assets with the greatest unrealized capital gain. Thus, upon the beneficiary’s death, assuming the beneficiary has available estate tax exclusion, property of the trust equal in value to the unused exclusion amount with the greatest built-in capital gain would receive a step-up in basis, yet no estate tax would be due. Alternatively, the terms of the trust could designate a so-called trust protector who has the authority to confer a formulaic general power of appointment upon a beneficiary should the circumstances favor such a provision.
It may also be possible to modify an existing irrevocable trust to add a formulaic general power of appointment or add a trust protector who can confer general powers of appointment to take advantage of the technique described above. Depending on the state law governing the trust, it may be possible to modify the trust through judicial modification (when a court changes a trust), non-judicial settlement (when the beneficiaries and trustees agree to change the terms of a trust) and decanting (when the trustee exercises a power in its discretion to distribute the trust to another trust).
Still further, if the beneficiary already has been granted a limited power of appointment over the assets of the trust, depending on the state law governing the trust, it may be possible to exercise even a limited power of appointment to cause some or all of the trust’s assets to be subject to transfer tax when the beneficiary dies. To do this, the beneficiary would exercise the original power of appointment in a way that creates a second power of appointment so that second power of appointment can be exercised to prevent the property subject to the power from being owned by someone outright or being transferred for a period of time that does not reference the date upon which the original power of appointment was created.[14] This is colloquially known as “springing the Delaware tax trap.” Nevertheless, the laws of some states prevent the trap from being sprung. Before attempting to spring the Delaware tax trap, consult an attorney in the state whose law governs the trust.
* This hypothetical is for illustrative purposes only. Tax calculations have been simplified for illustrative purposes and do not take into account any tax attributes that may affect a taxpayer's particular situation (for example state and local taxes, marital status, or exemptions).
Table 1: Benefit of Avoiding Estate Tax by Generation*
Trust Not Exempt
50
100
150
200
Trust Property
$1,500,000
$10,660,025
$41,666,582
$162,861,163
$636,571,495
Estate/GSTT Tax
($4,797,011)
($18,749,962)
($73,287,524)
($286,457,173)
Balance in Trust
$1,500,000
$5,863,014
$22,916,620
$89,573,640
$350,114,322
Table 2: Benefit of Avoiding Estate Tax by Generation*
Trust Exempt from Transfer Taxes
Year
1 (Creation)
50
100
150
200
Trust Property
$1,500,000
$10,660,025
$75,757,422
$538,384,011
$3,826,124,687
Estate/GSTT Tax
$0
$0
$0
$0
Balance in Trust
$1,500,000
$10,660,025
$75,757,422
$538,384,011
$3,826,124,687
Benefit to Family
$0
$4,797,011
$52,840,802
$448,810,371
$3,476,010,365
A federal estate and/or generation-skipping transfer tax (GSTT). Tax is imposed every 50 years. The federal estate and/or GSTT Tax Rate is 40%. Trust property grows at 4% each year (after federal income tax).
A Flexible, but Complex, Tool
Powers of appointment are powerful planning tools. They can be included in your plan documents at the outset or, depending on applicable state law, added to the terms of an existing irrevocable trust through a modification.
Powers of appointment can be customized to fit your and your family’s particular circumstances. Adding a power of appointment to your plan provides your beneficiaries with the ability to alter the plan to fit changing circumstances.
However, because powers of appointment are powerful, customizable and can have a large impact on taxation, you should consult with your legal, tax and financial advisors when considering adding powers of appointment to a new plan or modifying an old plan to include them.
The annual exclusion amount permits donors to give without facing a gift tax. What should you consider in regards to annual exclusion gifting?
Jun 20 2023 | 3 min read

The federal government imposes a tax on gifts. However, Congress has permitted donors to give a small amount to each beneficiary of their choosing before facing the federal gift tax. This amount is known as the annual exclusion amount, which for 2023 is $17,000 per beneficiary.
The value of all gifts made during the year to a single beneficiary count towards the donor’s $17,000 annual exclusion, no matter what their form. Thus, if you give your child a $10,000 automobile, you have used $10,000 of your annual exclusion and have $7,000 left to give that child within the annual exclusion amount.
Special rules apply to married couples. Two spouses can “split” a gift to a single beneficiary and treat it as if one-half of the total was made by each spouse, no matter which spouse actually made the gift. This technique allows one spouse to make gifts using both spouses’ annual exclusions, for a total gift of $34,000. To qualify for gift splitting, the spouses must file federal gift tax returns signed by both spouses consenting to the split, even if a return would not otherwise be necessary were each to give $17,000 individually.
Your gift must be “complete” by year-end. If making a gift of cash by check close to the end of the calendar year, the check should be cashed before December 31. The gift will not be complete during the time you can stop payment on your check. It is best not to create uncertainty. If making a cash gift right at the end of the year, to avoid any question as to when the gift is complete, consider using a certified check, bank check or, perhaps, a prepaid gift card.
A gift must be of a “present interest in property” to qualify for this exclusion from the gift tax. These are gifts that the beneficiary can access and use immediately.
A gift in trust that benefits the beneficiary only if a trustee makes a distribution from the trust cannot be readily accessed and is not a present interest in property.
Nevertheless, some gifts in trusts can qualify for the annual exclusion, as described below.
· Minor’s Trust under Section 2503(c): Gifts to a minor’s trusts created for a beneficiary under the age of 21 pursuant to Internal Revenue Code §2503(c) will qualify for the annual exclusion. To qualify as a §2503(c) minor’s trust, prior to the beneficiary attaining age 21, distributions may be made only to the beneficiary, the beneficiary must be able to take all property from the trust at age 21, and if the beneficiary dies before attaining age 21, the value of the trust property must be included in the beneficiary’s gross estate either by being paid to the beneficiary’s estate or pursuant to a general power of appointment held by the beneficiary.
· “Crummey” Trust: Gifts to a so-called “Crummey” Trust, that allows the beneficiary (or an adult acting on a minor beneficiary’s behalf) to withdraw a gift to the trust for a limited time after the gift is made, will also qualify for the annual exclusion. Sometimes, depending on the value of the trust, the lapse of the beneficiary’s power to withdraw property from the trust could cause the beneficiary (even if the beneficiary is a minor) to make a taxable gift. Accordingly, care should be used when deciding when and how much of a beneficiary’s withdrawal right should lapse in any one year.
Gifts to grandchildren and more remote descendants could also cause the imposition of a generation-skipping transfer tax (GSTT). This is an additional tax imposed on gifts made to persons two or more generations below the transferor.
Outright gifts to a grandchild or more remote descendant up to the annual exclusion amount are nontaxable gifts and are generally not subject to the GSTT.
Gifts made to a trust for a grandchild do not qualify for this treatment unless the trust is for a grandchild or more remote descendant and during the life of such beneficiary, no portion of the corpus or income of the trust may be distributed to, or for the benefit of, any person other than the beneficiary, and if the trust does not terminate before the beneficiary dies, the assets of such trust will be includable in the beneficiary’s gross estate.
Always remember to consult your attorney and financial advisors when making gifts or creating trusts.
design sophisticated, customized plans that can help you achieve a careful balance of control and flexibility, shaping your family's future while responding to its changing needs. We can assist you with:
What Estate Planning Documents Do I Need and Why?
Many people assume having a will is sufficient, but estate planning is more than just preparing a will. An estate plan typically should, at a minimum, include both financial and health care powers of attorney, a Health Insurance Portability and Accountability Act of 1996 (HIPAA) waiver, and living will. While a will can provide for the disposition of your assets upon your death, it is not legally effective to deal with a variety of other situations that could arise during your lifetime, such as incapacity and the need for someone to make medical or legal decisions on your behalf.
In keeping with a goals-based approach, estate planning should incorporate an integrated approach to determine which documents may be necessary to accomplish your objectives.
The documents you may want to consider including in your plan are set out below.
A Will
A will is a legal document that allows you to direct the distribution of your property following your death. Without a will your state’s intestacy statute will dictate who receives your property (which may not reflect how you want your assets to be distributed). For example, do you want a child to receive a large sum of money at age 18? What if you have a child or a spouse with special needs? Do you want an estranged family member with whom you have no relationship to receive assets that you have earmarked for a child or other beneficiaries?
In addition, a will gives you the ability to appoint a guardian for your minor children. Although the ultimate decision as to the appointment of a guardian rests with the appropriate court, by appointing a guardian in your will, you provide the judge with your preferences and may minimize the possibility of family conflict over who should care for your children. When choosing a guardian, you may want to consider not only those willing and qualified to take the job, but individuals who share your values and way of life.
Further, a will allows you to appoint an executor to oversee the distribution of your assets — the person who will be charged with carrying out your wishes when you are not here to do so yourself. You may want to keep in mind that acting as an executor is not an honor; rather, it is a job which requires completion of critical duties. Before you choose an executor (also known as a personal representative), you may want to weigh not only the qualifications of the individual but whether they have the time to devote to the numerous legal and tax duties required of the position. For many, appointing an individual as personal representative together with an institution can provide the right balance of technical experience and familial context.
Financial Power of Attorney
If you own any assets or property in your own name, you may wish to create a financial power of attorney. When you own an asset in your own name (for example, real estate, a bank account, or an investment account), only you have authority over this asset. If you are unable to make decisions regarding your assets, you may need to delegate authority to someone else to handle those assets should the need arise.
A financial power of attorney appoints an individual, commonly referred to as your “agent,” to handle your financial affairs should you become incapacitated or unable to handle day-to-day decision making.
Your agent will be able to act on your behalf by paying your bills, making investment decisions, handling tax and real estate matters, depositing money, and transacting other personal business you would otherwise have handled yourself. Without such a document, it may be necessary for a court to appoint someone on your behalf to handle these matters. Generally speaking, many people would prefer to choose who will make these decisions for them should the need arise rather than having a court make that choice. A financial power of attorney gives you that ability.
When Your Children Become Adults
Once a child attains the age of 18, the child is an adult and a parent can no longer access their medical records or make medical decisions on their behalf without special legal documents. A health care power of attorney naming someone (presumably the parent(s)) as a child’s medical agent will give the named individual(s) the ability to make medical decisions on behalf of the child should the child be unable to do so for themselves. Think about how it would be if you, as a parent, were not able to give or refuse consent for treatment or be able to gain access to medical information.
A HIPAA authorization is another “must have” document for college-aged children. A form signed by your child will permit you to receive information from health care providers about the child’s health and treatment.
Health Care Power of Attorney
Much like a financial power of attorney, a health care power of attorney allows you to designate someone (your agent) to make medical decisions for you should you be unable to make them for yourself.
If you are over the age of 18 and do not have a health care power of attorney, if you are incapacitated a petition will need to be filed with the appropriate court and a judge will appoint a guardian to make you health care decisions. Potentially, this could lead to unnecessary cost and delay which may be avoidable with the correct documents. Again, would you prefer a stranger to make these decisions, or would you rather determine who will have this ability.
A Living Will
If you are over 18 years of age, you may want to create a living will. A living will, also known as an advance health care directive, allows you to specify what end-of-life treatment you do or do not want to receive if you become terminally ill or permanently unconscious and will not survive without the administration of life support. A living will takes the decision to remove life support out of the hands of family members during a very emotional time by stating your wishes in advance.
HIPAA Waiver
If you are over the age of 18, you may want a HIPAA Waiver. While your health care power of attorney and advance health care directive will likely contain language that allows your agent to access your medical records, it is not uncommon for medical facilities to refuse access to medical information without a stand-alone HIPAA waiver. This back up document allows your family members to have access to your medical information so they can speak freely with your health care providers in case of a medical emergency or your incapacity.
If I Already Have Estate Planning Documents, Do I Need to Do Anything?
Your estate planning documents may be the most important documents you will ever write. Often though, after being executed, they are put away for safekeeping and not looked at again. That can be a mistake. You may want to review your plan regularly as your life evolves to determine if your documents still accurately reflect your goals. For example, consider the following common, but important, reasons for contemplating updates to your existing documents:
Next Steps – Create your ICE Pack (In Case of Emergency)
Remember, even the most carefully drafted documents will be of no value if your loved ones do not know where they are located. Consider creating the following, in case an emergency arises.
1. A folder containing copies of your estate planning documents, which someone knows how to find.
2. A special envelope containing your health care documents that is easily accessible should you need to be hospitalized. You may also want to have a copy of your Health Care Directive/Living Will on file with your personal physician and local hospital.
3. Lists of important information for your loved ones to easily access:
· Relevant personal contacts who should be notified in the case of an emergency.
· Assets, debts, expenses, account information, health care and life insurance documentation, as well as other important information should your designated agent, under either a financial or health care power of attorney, need to act on your behalf.
· Online accounts and their usernames/ passwords so that electronically stored photos, videos, email and social media accounts, as well as online accounts with various financial institutions, can be accessed.
· Medical history, medications, and health issues for your health care power of attorney agent(s). Also, do not overlook the importance of having a conversation with your designated agent regarding your wishes.
Finally, do the individuals named in your documents know you have chosen them to serve in a fiduciary capacity? Before you name someone to take on any of these responsibilities, it is important to discuss this with them beforehand.
Conclusion
In these uncertain times, being proactive by putting appropriate and up-to-date estate planning documents in place can help alleviate stress and create a measure of certainty and peace of mind that will serve you and your family well in the years to come. Your PNC Private Bank® team is here and ready to work with you and your advisors.
When to Review Your Will – Checklist
In addition to regularly reviewing your will and estate planning documents every three to five years, you should also consider reviewing your estate plan when these situations and life events arise:
· Upon birth or adoption of a child, grandchild, or other family member
· Following a marriage or divorce
· When someone named in your will passes away
· When a child or grandchild needs educational funding
· When children, grandchildren, or other heirs reach adulthood
· Upon changes in your executor’s, guardian’s, and/or trustee’s circumstances
· When the value of your estate significantly increases or decreases
· The acquisition or disposition of a significant asset
· Upon starting a business or when contemplating the transfer of a business
· Following changes in tax laws
· When you are approaching age 72 (the age when you are required to begin taking distributions from your individual retirement account, 401(k), or other qualified plan)
· After a move to a different state
· If you are diagnosed with a chronic or terminal illness or disability
Planning Using Powers of Appointment
Through the years, the dynamics of your family will change. Your family may grow, children and grandchildren may be born, some offspring may mature into wise adults and some may not, some family members may suffer through illness (perhaps debilitating), and, at some point, every member of the family will die. Of course, changes come from outside of your family, too. Tax and property laws change from one Congress to the next. Unanticipated events occur in the economy or in the financial markets. Businesses may succeed wildly or fail spectacularly.
Given the inevitable changes over the course of a lifetime, you may ask:
· Can I create an estate plan that may be later adjusted for the inevitable changes of life?
· If I plan for today’s circumstances, is it possible to also plan for an uncertain future – even for events that occur after I have departed this life when my estate plan becomes irrevocable?
· Can I plan now to protect my family’s wealth for generations to come, while allowing the plan to take into consideration changed circumstances?
The answer to each of the foregoing questions is yes.
Indeed, it is possible to secure your wealth for future generations yet provide for an uncertain future, no matter what comes, by building flexibility into the plan documents.
While there are many ways to build flexibility into the irrevocable documents that create your plan, using a power of appointment makes your plan flexible by allowing future generations to adapt it to later circumstances.
What is a Power of Appointment?
An important part of any wealth plan is the transfer of wealth from members of senior generations to members of junior generations. Of course, your plan can give property outright to any person. However, doing so fails to protect that property from many risks. Property owned by an individual outright may be disposed of in any manner by such person. Property transferred outright is “unprotected” because it is subject to the claims of the owner’s creditors (possibly including those of a divorcing spouse), it may be invested imprudently and lost and it can be given away, including to persons outside your family. To protect your wealth from those and other circumstances, instead of giving your wealth to your beneficiaries outright, you could create trusts for their benefit. In fact, to protect your property for long periods of time, you can create trusts that last for (and benefit) many generations of your descendants. (Note that some states have laws that require trusts to end by a certain date.[1] Check with your attorney to see how the laws of your state could impact your plan.)
Irrevocable trusts for your beneficiaries are generally governed by the terms that you set when you create the trust. As trust law has developed, however, many states have adopted laws that allow irrevocable trusts to be changed. These laws include judicial modifications (when a court changes a trust), non-judicial settlements (when the beneficiaries and trustees agree to change the terms of a trust) and decanting (when the trustee exercises a power in its discretion to distribute the trust to another trust). Additionally, the terms of your trust can give your beneficiaries the ability to change the terms of the trust by conferring upon them a power of appointment.
A “power of appointment” is a right that the creator of a trust[2] (the donor) confers upon another person (the donee or power holder) to direct the disposition of specified property. The donor of the power of appointment sets the terms as to how the power can be exercised and the steps that the holder of the power must follow to exercise the power. If the power holder does not comply with the requirements of the power of appointment, its exercise could be void.
For example, a power of appointment may:
· be exercisable immediately, or at some time in the future (such as when its holder dies);
· restrict who may receive property when the power is exercised (such as limiting recipients to the donor’s descendants);
· set conditions on what the beneficiaries receive and how they receive it, such as requiring the power to be exercised to create another trust (and not transfer property outright); or
· restrict the mechanism for exercising the power (for example, by only allowing it to be exercised by the power holder’s will and by specific reference to the document creating the power of appointment).
Types of Powers of Appointment
Powers of appointment can be customized to suit your circumstances as well as those of your family.
However, for federal gift and estate tax (collectively, transfer tax) purposes, there are two types of powers of appointment:[3] a general power of appointment and a limited power of appointment.
· A general power of appointment allows the power holder to direct property to be distributed to any person or entity and subject to any condition as specified in the power of appointment, but the power holder must also have the ability to direct the property to be distributed to any of (i) the power holder, (ii) the power holder’s creditors, (iii) the power holder’s estate or (iv) the creditors of the power holder’s estate.[4]
· A limited power of appointment (also known as a special power of appointment) allows the power holder to direct the property to be distributed to any person or entity and subject to any condition as specified in the power of appointment other than (i) the power holder, (ii) the power holder’s creditors, (iii) the power holder’s estate or (iv) the creditors of the power holder’s estate. A limited power of appointment can be quite broad, as it can be drafted to allow the power holder to appoint the property subject to the power to anyone or any entity in the world other than the four above stated exceptions.
Ownership and Powers of Appointment
With limited exceptions, state law creates and governs interests in property and ownership rights.[5] The power holder must look to state law to determine what is owned and the rights conferred by such ownership. For example, a presently exercisable general power of appointment in favor of the power holder allows the power holder to “take” the property subject to the power of appointment. Such a power is the legal equivalent of ownership and subjects the property subject to the power of appointment to the claims of the power holder’s creditors. However, a general power of appointment exercisable by will may not be subject to the claims of the power holder’s creditors during life but could be subject to the power holder’s creditors at death. Conversely, a limited power of appointment (whether exercisable during life or at death) does not confer any economic benefit on the power holder and is not subject to the claims of the power holder’s creditors.[6] As the law of each state is different, you should consult with your attorney to determine ownership rights.
Tax Treatment of Powers of Appointment
Powers of appointment can have important tax consequences to the power holder. Generally, if the power holder dies holding a general power of appointment created after October 21, 1942 (whether the power of appointment is exercised or not), the value of the property subject to the power will be included in the power holder’s gross estate and potentially subject to federal estate tax.[7] The value of the property subject to a general power of appointment would also be included in the power holder’s gross estate if the power holder released or exercised the power under circumstances such that, had the power holder owned and transferred the property subject to the power of appointment, the property would be includible in the deceased power holder’s gross estate under certain other sections of the Internal Revenue Code (IRC).[8]
On the other hand, the value of property subject to a limited power of appointment will not be included in the power holder’s gross estate at death unless the power holder exercises the original power of appointment to
· create a second power of appointment, and
· the second power of appointment can be exercised to prevent the property subject to the second power from being owned outright or being transferred, and
· the period of time during which the property cannot be owned outright or transferred does not reference the date the original power was created.[9]
For gift tax purposes, the exercise or release of a general power of appointment created after October 21, 1942, will be deemed a transfer of property by the power holder and potentially subject to gift tax, unless the value of the property subject to the power that lapses or is released is less than the greater of $5,000 or 5% of the total value of the property subject to the power of appointment.[10]
For income tax purposes:
· to the extent property is included in the gross estate of the power holder, its tax cost basis will become its fair market value at death. The basis of appreciated property will “step up” to its then-fair market value, whereas the basis of depreciated property will be “stepped down.”
· in some cases a trust beneficiary who holds a presently exercisable power of appointment allowing the beneficiary to take the property in a trust (or who had such a power that has lapsed but has certain rights over the trust) can be treated as owning the property in the trust for income tax purposes (making the trust a so-called grantor trust).[11]
Using Powers of Appointment
As circumstances change, powers of appointment can provide flexibility to your plan. There are many ways to use powers of appointment to the advantage of your family. Following are some examples.
As circumstances change, powers of appointment can provide flexibility to your plan. There are many ways to use powers of appointment to the advantage of your family.
Unexpected Problems Arise After Death
Planning for Changed Circumstances
Spouse 1 dies, leaving a trust for the benefit of Spouse 2. The trust requires that its income be paid to Spouse 2 at least annually for life and gives the trustee the discretion to distribute principal to Spouse 2. Spouse 2 also is granted a limited power of appointment to direct the trust property to be distributed outright or in further trust for any of the Spouse 1’s descendants at Spouse 2’s death. If the power is not exercised, the assets remaining in the trust will be distributed outright to the descendants of Spouse 1, per stirpes. Assume that Spouse 1 has two children. Further assume that the oldest child of Spouse 1 develops a substance abuse problem after Spouse 1 died.
Upon Spouse 2’s death, if nothing is done, each of the children would receive one-half of the trust property, outright. In that case, property received by the older child could perpetuate, or even exacerbate, the substance abuse issues. Instead, Spouse 2 could exercise the power of appointment, requiring the oldest child’s share to be held in a trust, to provide for that child (even to the point of paying for treatment). The oldest child’s share would be protected from that child’s potential improvidence, shielded from that child’s creditors and available to care for that child. Moreover, the property would be unavailable to feed that child’s self-destructive behavior.
Special Needs
Using the same facts as outlined above, assume that after Spouse 1 died, the younger child has a child (grandchild) with severe disabilities who will require professional care for life. If the grandchild were to receive property from the trust, such a distribution could disqualify the grandchild from receiving public assistance. Ignoring tax consequences for the moment, assume Spouse 2 and the younger child plan together that Spouse 2 should provide some funds to care for the grandchild upon Spouse 2’s death. In that case, Spouse 2 could exercise the power of appointment in such a way as to provide a trust that could be used in part for the younger child and in part to provide the grandchild with services and items not provided by government assistance. Further, the power could be exercised so that upon the younger child’s death, whatever property remained in the child’s trust would continue in a trust to provide the grandchild with services and items not provided by government assistance for the rest of grandchild’s life. Upon the grandchild’s subsequent death, if there is property remaining in the trust, the exercise of the power would specify which of the descendants of Spouse 1 would receive the property and the conditions upon which it would be received. For example, if the younger child had no other descendants, any remaining property could be added to the trust for the older child.
Financial Windfall
Assume the same facts as outlined above, except that the younger child has children (grandchildren), none of whom have special needs. Further assume that the younger child was a business owner who sold the business for hundreds of millions of dollars. If Spouse 2 takes no action, upon the death of Spouse 2 one-half of the trust would be paid outright to the younger child. This would augment younger child’s estate, which (based on current law) would be subject to a substantial estate tax. Ignoring taxes for the moment, because the younger child already has a large estate, perhaps Spouse 2 could exercise the power of appointment to create trusts for the grandchildren.
Limitations on Exercise
In each of the foregoing examples, because the power of appointment restricted the possible appointees to the descendants of Spouse 1, Spouse 2 could not have directed the trust to be distributed to anyone or any entity other than a descendant of Spouse 1. If the power of appointment had allowed trust assets to be distributed “to any person or entity other than Spouse 2, Spouse 2’s creditors, Spouse 2’s estate or the creditors of Spouse 2’s estate,” Spouse 2 could have directed the entire trust to be distributed to any person or entity (either outright or in trust) other than the four entities prohibited from receiving property. In that case, even though that power of appointment would still have been a limited power of appointment, the group of potential appointees would have been so broad that Spouse 2 could have caused the property to be distributed to virtually anyone, including a new spouse, the new spouse’s children or a charitable organization. Thus, great care should be taken when drafting powers of appointment to balance flexibility with the desire to keep wealth within the family.
Tax Planning with Powers of Appointment
Taxpayers create extensive plans to minimize their overall tax liabilities. As one of America’s great jurists once wrote: “Any one (sic) may so arrange his affairs that his taxes shall be as low as possible; he is not bound to choose that pattern which will best pay the Treasury; there is not even a patriotic duty to increase one’s taxes.”[12]
For decades, taxpayers have used trusts to minimize the amount of transfer taxes required to be paid by each generation of their families. Many of these strategies involve long-term trusts.
These trusts are designed to last for many generations, without being subject to transfer taxes. (Although beyond the scope of this article, usually the transferor has allocated exemption from the generation-skipping transfer tax to the trust so that it has an inclusion ratio of zero, or the trust was irrevocable before September 25, 1985.) This means that the terms of the trusts are crafted so that the value of the trust’s property is not included in the gross estate of any beneficiary who dies. The benefit of avoiding estate tax at each generation is illustrated by the table on page 5.
However, avoiding transfer taxes by holding property in a long-term trust may cause an income tax issue. As the assets in the trust appreciate, the unrealized capital gain in the assets grows. Because the assets of the trust are not considered to be transferred by the trust’s beneficiaries, the assets in the trust never receive a so-called basis step up as each beneficiary dies.[13]
In 2022, each citizen and resident of the United States has an exclusion from the federal estate tax of $12.06 million. This exclusion amount represents a significant increase from exclusion amounts of previous years. In fact, as late as 2002, the exclusion amount was only $1 million. As estate tax exclusion amounts have grown, fewer taxpayers have been subject to the federal estate tax.
Is it possible to both avoid transfer taxes and get a step-up in basis to reduce capital gain tax? To some extent, the answer is yes.
When creating a new estate plan, you could create trusts that optimize both transfer tax and capital gains tax savings. To do so, the terms of your trust could grant its beneficiaries a carefully crafted general power of appointment. Each beneficiary would have a general power of appointment (exercisable when the beneficiary dies) over an amount of property in the trust determined by a formula. The formula would limit the amount of property subject to the power of appointment to the beneficiary’s available (or unused) estate tax exclusion amount (so that no estate tax would be paid). Further, the formula would apply to those assets with the greatest unrealized capital gain. Thus, upon the beneficiary’s death, assuming the beneficiary has available estate tax exclusion, property of the trust equal in value to the unused exclusion amount with the greatest built-in capital gain would receive a step-up in basis, yet no estate tax would be due. Alternatively, the terms of the trust could designate a so-called trust protector who has the authority to confer a formulaic general power of appointment upon a beneficiary should the circumstances favor such a provision.
It may also be possible to modify an existing irrevocable trust to add a formulaic general power of appointment or add a trust protector who can confer general powers of appointment to take advantage of the technique described above. Depending on the state law governing the trust, it may be possible to modify the trust through judicial modification (when a court changes a trust), non-judicial settlement (when the beneficiaries and trustees agree to change the terms of a trust) and decanting (when the trustee exercises a power in its discretion to distribute the trust to another trust).
Still further, if the beneficiary already has been granted a limited power of appointment over the assets of the trust, depending on the state law governing the trust, it may be possible to exercise even a limited power of appointment to cause some or all of the trust’s assets to be subject to transfer tax when the beneficiary dies. To do this, the beneficiary would exercise the original power of appointment in a way that creates a second power of appointment so that second power of appointment can be exercised to prevent the property subject to the power from being owned by someone outright or being transferred for a period of time that does not reference the date upon which the original power of appointment was created.[14] This is colloquially known as “springing the Delaware tax trap.” Nevertheless, the laws of some states prevent the trap from being sprung. Before attempting to spring the Delaware tax trap, consult an attorney in the state whose law governs the trust.
* This hypothetical is for illustrative purposes only. Tax calculations have been simplified for illustrative purposes and do not take into account any tax attributes that may affect a taxpayer's particular situation (for example state and local taxes, marital status, or exemptions).
Table 1: Benefit of Avoiding Estate Tax by Generation*
Trust Not Exempt from Transfer Taxes
Year
1 (Creation)
50
100
150
200
Trust Property
$1,500,000
$10,660,025
$41,666,582
$162,861,163
$636,571,495
Estate/GSTT Tax
($4,797,011)
($18,749,962)
($73,287,524)
($286,457,173)
Balance in Trust
$1,500,000
$5,863,014
$22,916,620
$89,573,640
$350,114,322
Table 2: Benefit of Avoiding Estate Tax by Generation*
Trust Exempt from Transfer Taxes
Year
1 (Creation)
50
100
150
200
Trust Property
$1,500,000
$10,660,025
$75,757,422
$538,384,011
$3,826,124,687
Estate/GSTT Tax
$0
$0
$0
$0
Balance in Trust
$1,500,000
$10,660,025
$75,757,422
$538,384,011
$3,826,124,687
Benefit to Family
$0
$4,797,011
$52,840,802
$448,810,371
$3,476,010,365
A federal estate and/or generation-skipping transfer tax (GSTT). Tax is imposed every 50 years. The federal estate and/or GSTT Tax Rate is 40%. Trust property grows at 4% each year (after federal income tax).
A Flexible, but Complex, Tool
Powers of appointment are powerful planning tools. They can be included in your plan documents at the outset or, depending on applicable state law, added to the terms of an existing irrevocable trust through a modification.
Powers of appointment can be customized to fit your and your family’s particular circumstances. Adding a power of appointment to your plan provides your beneficiaries with the ability to alter the plan to fit changing circumstances.
However, because powers of appointment are powerful, customizable and can have a large impact on taxation, you should consult with your legal, tax and financial advisors when considering adding powers of appointment to a new plan or modifying an old plan to include them.
The annual exclusion amount permits donors to give without facing a gift tax. What should you consider in regards to annual exclusion gifting?
Jun 20 2023 | 3 min read
The federal government imposes a tax on gifts. However, Congress has permitted donors to give a small amount to each beneficiary of their choosing before facing the federal gift tax. This amount is known as the annual exclusion amount, which for 2023 is $17,000 per beneficiary.
The value of all gifts made during the year to a single beneficiary count towards the donor’s $17,000 annual exclusion, no matter what their form. Thus, if you give your child a $10,000 automobile, you have used $10,000 of your annual exclusion and have $7,000 left to give that child within the annual exclusion amount.
Special rules apply to married couples. Two spouses can “split” a gift to a single beneficiary and treat it as if one-half of the total was made by each spouse, no matter which spouse actually made the gift. This technique allows one spouse to make gifts using both spouses’ annual exclusions, for a total gift of $34,000. To qualify for gift splitting, the spouses must file federal gift tax returns signed by both spouses consenting to the split, even if a return would not otherwise be necessary were each to give $17,000 individually.
Your gift must be “complete” by year-end. If making a gift of cash by check close to the end of the calendar year, the check should be cashed before December 31. The gift will not be complete during the time you can stop payment on your check. It is best not to create uncertainty. If making a cash gift right at the end of the year, to avoid any question as to when the gift is complete, consider using a certified check, bank check or, perhaps, a prepaid gift card.
A gift must be of a “present interest in property” to qualify for this exclusion from the gift tax. These are gifts that the beneficiary can access and use immediately.
A gift in trust that benefits the beneficiary only if a trustee makes a distribution from the trust cannot be readily accessed and is not a present interest in property.
Nevertheless, some gifts in trusts can qualify for the annual exclusion, as described below.
· Minor’s Trust under Section 2503(c): Gifts to a minor’s trusts created for a beneficiary under the age of 21 pursuant to Internal Revenue Code §2503(c) will qualify for the annual exclusion. To qualify as a §2503(c) minor’s trust, prior to the beneficiary attaining age 21, distributions may be made only to the beneficiary, the beneficiary must be able to take all property from the trust at age 21, and if the beneficiary dies before attaining age 21, the value of the trust property must be included in the beneficiary’s gross estate either by being paid to the beneficiary’s estate or pursuant to a general power of appointment held by the beneficiary.
· “Crummey” Trust: Gifts to a so-called “Crummey” Trust, that allows the beneficiary (or an adult acting on a minor beneficiary’s behalf) to withdraw a gift to the trust for a limited time after the gift is made, will also qualify for the annual exclusion. Sometimes, depending on the value of the trust, the lapse of the beneficiary’s power to withdraw property from the trust could cause the beneficiary (even if the beneficiary is a minor) to make a taxable gift. Accordingly, care should be used when deciding when and how much of a beneficiary’s withdrawal right should lapse in any one year.
Gifts to grandchildren and more remote descendants could also cause the imposition of a generation-skipping transfer tax (GSTT). This is an additional tax imposed on gifts made to persons two or more generations below the transferor.
Outright gifts to a grandchild or more remote descendant up to the annual exclusion amount are nontaxable gifts and are generally not subject to the GSTT.
Gifts made to a trust for a grandchild do not qualify for this treatment unless the trust is for a grandchild or more remote descendant and during the life of such beneficiary, no portion of the corpus or income of the trust may be distributed to, or for the benefit of, any person other than the beneficiary, and if the trust does not terminate before the beneficiary dies, the assets of such trust will be includable in the beneficiary’s gross estate.
Always remember to consult your attorney and financial advisors when making gifts or creating trusts.
design sophisticated, customized plans that can help you achieve a careful balance of control and flexibility, shaping your family's future while responding to its changing needs. We can assist you with:
What Estate Planning Documents Do I Need and Why?
Many people assume having a will is sufficient, but estate planning is more than just preparing a will. An estate plan typically should, at a minimum, include both financial and health care powers of attorney, a Health Insurance Portability and Accountability Act of 1996 (HIPAA) waiver, and living will. While a will can provide for the disposition of your assets upon your death, it is not legally effective to deal with a variety of other situations that could arise during your lifetime, such as incapacity and the need for someone to make medical or legal decisions on your behalf.
In keeping with a goals-based approach, estate planning should incorporate an integrated approach to determine which documents may be necessary to accomplish your objectives.
The documents you may want to consider including in your plan are set out below.
A Will
A will is a legal document that allows you to direct the distribution of your property following your death. Without a will your state’s intestacy statute will dictate who receives your property (which may not reflect how you want your assets to be distributed). For example, do you want a child to receive a large sum of money at age 18? What if you have a child or a spouse with special needs? Do you want an estranged family member with whom you have no relationship to receive assets that you have earmarked for a child or other beneficiaries?
In addition, a will gives you the ability to appoint a guardian for your minor children. Although the ultimate decision as to the appointment of a guardian rests with the appropriate court, by appointing a guardian in your will, you provide the judge with your preferences and may minimize the possibility of family conflict over who should care for your children. When choosing a guardian, you may want to consider not only those willing and qualified to take the job, but individuals who share your values and way of life.
Further, a will allows you to appoint an executor to oversee the distribution of your assets — the person who will be charged with carrying out your wishes when you are not here to do so yourself. You may want to keep in mind that acting as an executor is not an honor; rather, it is a job which requires completion of critical duties. Before you choose an executor (also known as a personal representative), you may want to weigh not only the qualifications of the individual but whether they have the time to devote to the numerous legal and tax duties required of the position. For many, appointing an individual as personal representative together with an institution can provide the right balance of technical experience and familial context.
Financial Power of Attorney
If you own any assets or property in your own name, you may wish to create a financial power of attorney. When you own an asset in your own name (for example, real estate, a bank account, or an investment account), only you have authority over this asset. If you are unable to make decisions regarding your assets, you may need to delegate authority to someone else to handle those assets should the need arise.
A financial power of attorney appoints an individual, commonly referred to as your “agent,” to handle your financial affairs should you become incapacitated or unable to handle day-to-day decision making.
Your agent will be able to act on your behalf by paying your bills, making investment decisions, handling tax and real estate matters, depositing money, and transacting other personal business you would otherwise have handled yourself. Without such a document, it may be necessary for a court to appoint someone on your behalf to handle these matters. Generally speaking, many people would prefer to choose who will make these decisions for them should the need arise rather than having a court make that choice. A financial power of attorney gives you that ability.
When Your Children Become Adults
Once a child attains the age of 18, the child is an adult and a parent can no longer access their medical records or make medical decisions on their behalf without special legal documents. A health care power of attorney naming someone (presumably the parent(s)) as a child’s medical agent will give the named individual(s) the ability to make medical decisions on behalf of the child should the child be unable to do so for themselves. Think about how it would be if you, as a parent, were not able to give or refuse consent for treatment or be able to gain access to medical information.
A HIPAA authorization is another “must have” document for college-aged children. A form signed by your child will permit you to receive information from health care providers about the child’s health and treatment.
Health Care Power of Attorney
Much like a financial power of attorney, a health care power of attorney allows you to designate someone (your agent) to make medical decisions for you should you be unable to make them for yourself.
If you are over the age of 18 and do not have a health care power of attorney, if you are incapacitated a petition will need to be filed with the appropriate court and a judge will appoint a guardian to make you health care decisions. Potentially, this could lead to unnecessary cost and delay which may be avoidable with the correct documents. Again, would you prefer a stranger to make these decisions, or would you rather determine who will have this ability.
A Living Will
If you are over 18 years of age, you may want to create a living will. A living will, also known as an advance health care directive, allows you to specify what end-of-life treatment you do or do not want to receive if you become terminally ill or permanently unconscious and will not survive without the administration of life support. A living will takes the decision to remove life support out of the hands of family members during a very emotional time by stating your wishes in advance.
HIPAA Waiver
If you are over the age of 18, you may want a HIPAA Waiver. While your health care power of attorney and advance health care directive will likely contain language that allows your agent to access your medical records, it is not uncommon for medical facilities to refuse access to medical information without a stand-alone HIPAA waiver. This back up document allows your family members to have access to your medical information so they can speak freely with your health care providers in case of a medical emergency or your incapacity.
If I Already Have Estate Planning Documents, Do I Need to Do Anything?
Your estate planning documents may be the most important documents you will ever write. Often though, after being executed, they are put away for safekeeping and not looked at again. That can be a mistake. You may want to review your plan regularly as your life evolves to determine if your documents still accurately reflect your goals. For example, consider the following common, but important, reasons for contemplating updates to your existing documents:
Next Steps – Create your ICE Pack (In Case of Emergency)
Remember, even the most carefully drafted documents will be of no value if your loved ones do not know where they are located. Consider creating the following, in case an emergency arises.
1. A folder containing copies of your estate planning documents, which someone knows how to find.
2. A special envelope containing your health care documents that is easily accessible should you need to be hospitalized. You may also want to have a copy of your Health Care Directive/Living Will on file with your personal physician and local hospital.
3. Lists of important information for your loved ones to easily access:
· Relevant personal contacts who should be notified in the case of an emergency.
· Assets, debts, expenses, account information, health care and life insurance documentation, as well as other important information should your designated agent, under either a financial or health care power of attorney, need to act on your behalf.
· Online accounts and their usernames/ passwords so that electronically stored photos, videos, email and social media accounts, as well as online accounts with various financial institutions, can be accessed.
· Medical history, medications, and health issues for your health care power of attorney agent(s). Also, do not overlook the importance of having a conversation with your designated agent regarding your wishes.
Finally, do the individuals named in your documents know you have chosen them to serve in a fiduciary capacity? Before you name someone to take on any of these responsibilities, it is important to discuss this with them beforehand.
Conclusion
In these uncertain times, being proactive by putting appropriate and up-to-date estate planning documents in place can help alleviate stress and create a measure of certainty and peace of mind that will serve you and your family well in the years to come. Your PNC Private Bank® team is here and ready to work with you and your advisors.
When to Review Your Will – Checklist
In addition to regularly reviewing your will and estate planning documents every three to five years, you should also consider reviewing your estate plan when these situations and life events arise:
· Upon birth or adoption of a child, grandchild, or other family member
· Following a marriage or divorce
· When someone named in your will passes away
· When a child or grandchild needs educational funding
· When children, grandchildren, or other heirs reach adulthood
· Upon changes in your executor’s, guardian’s, and/or trustee’s circumstances
· When the value of your estate significantly increases or decreases
· The acquisition or disposition of a significant asset
· Upon starting a business or when contemplating the transfer of a business
· Following changes in tax laws
· When you are approaching age 72 (the age when you are required to begin taking distributions from your individual retirement account, 401(k), or other qualified plan)
· After a move to a different state
· If you are diagnosed with a chronic or terminal illness or disability
Planning Using Powers of Appointment
Through the years, the dynamics of your family will change. Your family may grow, children and grandchildren may be born, some offspring may mature into wise adults and some may not, some family members may suffer through illness (perhaps debilitating), and, at some point, every member of the family will die. Of course, changes come from outside of your family, too. Tax and property laws change from one Congress to the next. Unanticipated events occur in the economy or in the financial markets. Businesses may succeed wildly or fail spectacularly.
Given the inevitable changes over the course of a lifetime, you may ask:
· Can I create an estate plan that may be later adjusted for the inevitable changes of life?
· If I plan for today’s circumstances, is it possible to also plan for an uncertain future – even for events that occur after I have departed this life when my estate plan becomes irrevocable?
· Can I plan now to protect my family’s wealth for generations to come, while allowing the plan to take into consideration changed circumstances?
The answer to each of the foregoing questions is yes.
Indeed, it is possible to secure your wealth for future generations yet provide for an uncertain future, no matter what comes, by building flexibility into the plan documents.
While there are many ways to build flexibility into the irrevocable documents that create your plan, using a power of appointment makes your plan flexible by allowing future generations to adapt it to later circumstances.
What is a Power of Appointment?
An important part of any wealth plan is the transfer of wealth from members of senior generations to members of junior generations. Of course, your plan can give property outright to any person. However, doing so fails to protect that property from many risks. Property owned by an individual outright may be disposed of in any manner by such person. Property transferred outright is “unprotected” because it is subject to the claims of the owner’s creditors (possibly including those of a divorcing spouse), it may be invested imprudently and lost and it can be given away, including to persons outside your family. To protect your wealth from those and other circumstances, instead of giving your wealth to your beneficiaries outright, you could create trusts for their benefit. In fact, to protect your property for long periods of time, you can create trusts that last for (and benefit) many generations of your descendants. (Note that some states have laws that require trusts to end by a certain date.[1] Check with your attorney to see how the laws of your state could impact your plan.)
Irrevocable trusts for your beneficiaries are generally governed by the terms that you set when you create the trust. As trust law has developed, however, many states have adopted laws that allow irrevocable trusts to be changed. These laws include judicial modifications (when a court changes a trust), non-judicial settlements (when the beneficiaries and trustees agree to change the terms of a trust) and decanting (when the trustee exercises a power in its discretion to distribute the trust to another trust). Additionally, the terms of your trust can give your beneficiaries the ability to change the terms of the trust by conferring upon them a power of appointment.
A “power of appointment” is a right that the creator of a trust[2] (the donor) confers upon another person (the donee or power holder) to direct the disposition of specified property. The donor of the power of appointment sets the terms as to how the power can be exercised and the steps that the holder of the power must follow to exercise the power. If the power holder does not comply with the requirements of the power of appointment, its exercise could be void.
For example, a power of appointment may:
· be exercisable immediately, or at some time in the future (such as when its holder dies);
· restrict who may receive property when the power is exercised (such as limiting recipients to the donor’s descendants);
· set conditions on what the beneficiaries receive and how they receive it, such as requiring the power to be exercised to create another trust (and not transfer property outright); or
· restrict the mechanism for exercising the power (for example, by only allowing it to be exercised by the power holder’s will and by specific reference to the document creating the power of appointment).
Types of Powers of Appointment
Powers of appointment can be customized to suit your circumstances as well as those of your family.
However, for federal gift and estate tax (collectively, transfer tax) purposes, there are two types of powers of appointment:[3] a general power of appointment and a limited power of appointment.
· A general power of appointment allows the power holder to direct property to be distributed to any person or entity and subject to any condition as specified in the power of appointment, but the power holder must also have the ability to direct the property to be distributed to any of (i) the power holder, (ii) the power holder’s creditors, (iii) the power holder’s estate or (iv) the creditors of the power holder’s estate.[4]
· A limited power of appointment (also known as a special power of appointment) allows the power holder to direct the property to be distributed to any person or entity and subject to any condition as specified in the power of appointment other than (i) the power holder, (ii) the power holder’s creditors, (iii) the power holder’s estate or (iv) the creditors of the power holder’s estate. A limited power of appointment can be quite broad, as it can be drafted to allow the power holder to appoint the property subject to the power to anyone or any entity in the world other than the four above stated exceptions.
Ownership and Powers of Appointment
With limited exceptions, state law creates and governs interests in property and ownership rights.[5] The power holder must look to state law to determine what is owned and the rights conferred by such ownership. For example, a presently exercisable general power of appointment in favor of the power holder allows the power holder to “take” the property subject to the power of appointment. Such a power is the legal equivalent of ownership and subjects the property subject to the power of appointment to the claims of the power holder’s creditors. However, a general power of appointment exercisable by will may not be subject to the claims of the power holder’s creditors during life but could be subject to the power holder’s creditors at death. Conversely, a limited power of appointment (whether exercisable during life or at death) does not confer any economic benefit on the power holder and is not subject to the claims of the power holder’s creditors.[6] As the law of each state is different, you should consult with your attorney to determine ownership rights.
Tax Treatment of Powers of Appointment
Powers of appointment can have important tax consequences to the power holder. Generally, if the power holder dies holding a general power of appointment created after October 21, 1942 (whether the power of appointment is exercised or not), the value of the property subject to the power will be included in the power holder’s gross estate and potentially subject to federal estate tax.[7] The value of the property subject to a general power of appointment would also be included in the power holder’s gross estate if the power holder released or exercised the power under circumstances such that, had the power holder owned and transferred the property subject to the power of appointment, the property would be includible in the deceased power holder’s gross estate under certain other sections of the Internal Revenue Code (IRC).[8]
On the other hand, the value of property subject to a limited power of appointment will not be included in the power holder’s gross estate at death unless the power holder exercises the original power of appointment to
· create a second power of appointment, and
· the second power of appointment can be exercised to prevent the property subject to the second power from being owned outright or being transferred, and
· the period of time during which the property cannot be owned outright or transferred does not reference the date the original power was created.[9]
For gift tax purposes, the exercise or release of a general power of appointment created after October 21, 1942, will be deemed a transfer of property by the power holder and potentially subject to gift tax, unless the value of the property subject to the power that lapses or is released is less than the greater of $5,000 or 5% of the total value of the property subject to the power of appointment.[10]
For income tax purposes:
· to the extent property is included in the gross estate of the power holder, its tax cost basis will become its fair market value at death. The basis of appreciated property will “step up” to its then-fair market value, whereas the basis of depreciated property will be “stepped down.”
· in some cases a trust beneficiary who holds a presently exercisable power of appointment allowing the beneficiary to take the property in a trust (or who had such a power that has lapsed but has certain rights over the trust) can be treated as owning the property in the trust for income tax purposes (making the trust a so-called grantor trust).[11]
Using Powers of Appointment
As circumstances change, powers of appointment can provide flexibility to your plan. There are many ways to use powers of appointment to the advantage of your family. Following are some examples.
As circumstances change, powers of appointment can provide flexibility to your plan. There are many ways to use powers of appointment to the advantage of your family.
Unexpected Problems Arise After Death
Planning for Changed Circumstances
Spouse 1 dies, leaving a trust for the benefit of Spouse 2. The trust requires that its income be paid to Spouse 2 at least annually for life and gives the trustee the discretion to distribute principal to Spouse 2. Spouse 2 also is granted a limited power of appointment to direct the trust property to be distributed outright or in further trust for any of the Spouse 1’s descendants at Spouse 2’s death. If the power is not exercised, the assets remaining in the trust will be distributed outright to the descendants of Spouse 1, per stirpes. Assume that Spouse 1 has two children. Further assume that the oldest child of Spouse 1 develops a substance abuse problem after Spouse 1 died.
Upon Spouse 2’s death, if nothing is done, each of the children would receive one-half of the trust property, outright. In that case, property received by the older child could perpetuate, or even exacerbate, the substance abuse issues. Instead, Spouse 2 could exercise the power of appointment, requiring the oldest child’s share to be held in a trust, to provide for that child (even to the point of paying for treatment). The oldest child’s share would be protected from that child’s potential improvidence, shielded from that child’s creditors and available to care for that child. Moreover, the property would be unavailable to feed that child’s self-destructive behavior.
Special Needs
Using the same facts as outlined above, assume that after Spouse 1 died, the younger child has a child (grandchild) with severe disabilities who will require professional care for life. If the grandchild were to receive property from the trust, such a distribution could disqualify the grandchild from receiving public assistance. Ignoring tax consequences for the moment, assume Spouse 2 and the younger child plan together that Spouse 2 should provide some funds to care for the grandchild upon Spouse 2’s death. In that case, Spouse 2 could exercise the power of appointment in such a way as to provide a trust that could be used in part for the younger child and in part to provide the grandchild with services and items not provided by government assistance. Further, the power could be exercised so that upon the younger child’s death, whatever property remained in the child’s trust would continue in a trust to provide the grandchild with services and items not provided by government assistance for the rest of grandchild’s life. Upon the grandchild’s subsequent death, if there is property remaining in the trust, the exercise of the power would specify which of the descendants of Spouse 1 would receive the property and the conditions upon which it would be received. For example, if the younger child had no other descendants, any remaining property could be added to the trust for the older child.
Financial Windfall
Assume the same facts as outlined above, except that the younger child has children (grandchildren), none of whom have special needs. Further assume that the younger child was a business owner who sold the business for hundreds of millions of dollars. If Spouse 2 takes no action, upon the death of Spouse 2 one-half of the trust would be paid outright to the younger child. This would augment younger child’s estate, which (based on current law) would be subject to a substantial estate tax. Ignoring taxes for the moment, because the younger child already has a large estate, perhaps Spouse 2 could exercise the power of appointment to create trusts for the grandchildren.
Limitations on Exercise
In each of the foregoing examples, because the power of appointment restricted the possible appointees to the descendants of Spouse 1, Spouse 2 could not have directed the trust to be distributed to anyone or any entity other than a descendant of Spouse 1. If the power of appointment had allowed trust assets to be distributed “to any person or entity other than Spouse 2, Spouse 2’s creditors, Spouse 2’s estate or the creditors of Spouse 2’s estate,” Spouse 2 could have directed the entire trust to be distributed to any person or entity (either outright or in trust) other than the four entities prohibited from receiving property. In that case, even though that power of appointment would still have been a limited power of appointment, the group of potential appointees would have been so broad that Spouse 2 could have caused the property to be distributed to virtually anyone, including a new spouse, the new spouse’s children or a charitable organization. Thus, great care should be taken when drafting powers of appointment to balance flexibility with the desire to keep wealth within the family.
Tax Planning with Powers of Appointment
Taxpayers create extensive plans to minimize their overall tax liabilities. As one of America’s great jurists once wrote: “Any one (sic) may so arrange his affairs that his taxes shall be as low as possible; he is not bound to choose that pattern which will best pay the Treasury; there is not even a patriotic duty to increase one’s taxes.”[12]
For decades, taxpayers have used trusts to minimize the amount of transfer taxes required to be paid by each generation of their families. Many of these strategies involve long-term trusts.
These trusts are designed to last for many generations, without being subject to transfer taxes. (Although beyond the scope of this article, usually the transferor has allocated exemption from the generation-skipping transfer tax to the trust so that it has an inclusion ratio of zero, or the trust was irrevocable before September 25, 1985.) This means that the terms of the trusts are crafted so that the value of the trust’s property is not included in the gross estate of any beneficiary who dies. The benefit of avoiding estate tax at each generation is illustrated by the table on page 5.
However, avoiding transfer taxes by holding property in a long-term trust may cause an income tax issue. As the assets in the trust appreciate, the unrealized capital gain in the assets grows. Because the assets of the trust are not considered to be transferred by the trust’s beneficiaries, the assets in the trust never receive a so-called basis step up as each beneficiary dies.[13]
In 2022, each citizen and resident of the United States has an exclusion from the federal estate tax of $12.06 million. This exclusion amount represents a significant increase from exclusion amounts of previous years. In fact, as late as 2002, the exclusion amount was only $1 million. As estate tax exclusion amounts have grown, fewer taxpayers have been subject to the federal estate tax.
Is it possible to both avoid transfer taxes and get a step-up in basis to reduce capital gain tax? To some extent, the answer is yes.
When creating a new estate plan, you could create trusts that optimize both transfer tax and capital gains tax savings. To do so, the terms of your trust could grant its beneficiaries a carefully crafted general power of appointment. Each beneficiary would have a general power of appointment (exercisable when the beneficiary dies) over an amount of property in the trust determined by a formula. The formula would limit the amount of property subject to the power of appointment to the beneficiary’s available (or unused) estate tax exclusion amount (so that no estate tax would be paid). Further, the formula would apply to those assets with the greatest unrealized capital gain. Thus, upon the beneficiary’s death, assuming the beneficiary has available estate tax exclusion, property of the trust equal in value to the unused exclusion amount with the greatest built-in capital gain would receive a step-up in basis, yet no estate tax would be due. Alternatively, the terms of the trust could designate a so-called trust protector who has the authority to confer a formulaic general power of appointment upon a beneficiary should the circumstances favor such a provision.
It may also be possible to modify an existing irrevocable trust to add a formulaic general power of appointment or add a trust protector who can confer general powers of appointment to take advantage of the technique described above. Depending on the state law governing the trust, it may be possible to modify the trust through judicial modification (when a court changes a trust), non-judicial settlement (when the beneficiaries and trustees agree to change the terms of a trust) and decanting (when the trustee exercises a power in its discretion to distribute the trust to another trust).
Still further, if the beneficiary already has been granted a limited power of appointment over the assets of the trust, depending on the state law governing the trust, it may be possible to exercise even a limited power of appointment to cause some or all of the trust’s assets to be subject to transfer tax when the beneficiary dies. To do this, the beneficiary would exercise the original power of appointment in a way that creates a second power of appointment so that second power of appointment can be exercised to prevent the property subject to the power from being owned by someone outright or being transferred for a period of time that does not reference the date upon which the original power of appointment was created.[14] This is colloquially known as “springing the Delaware tax trap.” Nevertheless, the laws of some states prevent the trap from being sprung. Before attempting to spring the Delaware tax trap, consult an attorney in the state whose law governs the trust.
* This hypothetical is for illustrative purposes only. Tax calculations have been simplified for illustrative purposes and do not take into account any tax attributes that may affect a taxpayer's particular situation (for example state and local taxes, marital status, or exemptions).
Table 1: Benefit of Avoiding Estate Tax by Generation*
Trust Not Exempt from Transfer Taxes
Year
1 (Creation)
50
100
150
200
Trust Property
$1,500,000
$10,660,025
$41,666,582
$162,861,163
$636,571,495
Estate/GSTT Tax
($4,797,011)
($18,749,962)
($73,287,524)
($286,457,173)
Balance in Trust
$1,500,000
$5,863,014
$22,916,620
$89,573,640
$350,114,322
Table 2: Benefit of Avoiding Estate Tax by Generation*
Trust Exempt from Transfer Taxes
Year
1 (Creation)
50
100
150
200
Trust Property
$1,500,000
$10,660,025
$75,757,422
$538,384,011
$3,826,124,687
Estate/GSTT Tax
$0
$0
$0
$0
Balance in Trust
$1,500,000
$10,660,025
$75,757,422
$538,384,011
$3,826,124,687
Benefit to Family
$0
$4,797,011
$52,840,802
$448,810,371
$3,476,010,365
A federal estate and/or generation-skipping transfer tax (GSTT). Tax is imposed every 50 years. The federal estate and/or GSTT Tax Rate is 40%. Trust property grows at 4% each year (after federal income tax).
A Flexible, but Complex, Tool
Powers of appointment are powerful planning tools. They can be included in your plan documents at the outset or, depending on applicable state law, added to the terms of an existing irrevocable trust through a modification.
Powers of appointment can be customized to fit your and your family’s particular circumstances. Adding a power of appointment to your plan provides your beneficiaries with the ability to alter the plan to fit changing circumstances.
However, because powers of appointment are powerful, customizable and can have a large impact on taxation, you should consult with your legal, tax and financial advisors when considering adding powers of appointment to a new plan or modifying an old plan to include them.
The annual exclusion amount permits donors to give without facing a gift tax. What should you consider in regards to annual exclusion gifting?
Jun 20 2023 | 3 min read
The federal government imposes a tax on gifts. However, Congress has permitted donors to give a small amount to each beneficiary of their choosing before facing the federal gift tax. This amount is known as the annual exclusion amount, which for 2023 is $17,000 per beneficiary.
The value of all gifts made during the year to a single beneficiary count towards the donor’s $17,000 annual exclusion, no matter what their form. Thus, if you give your child a $10,000 automobile, you have used $10,000 of your annual exclusion and have $7,000 left to give that child within the annual exclusion amount.
Special rules apply to married couples. Two spouses can “split” a gift to a single beneficiary and treat it as if one-half of the total was made by each spouse, no matter which spouse actually made the gift. This technique allows one spouse to make gifts using both spouses’ annual exclusions, for a total gift of $34,000. To qualify for gift splitting, the spouses must file federal gift tax returns signed by both spouses consenting to the split, even if a return would not otherwise be necessary were each to give $17,000 individually.
Your gift must be “complete” by year-end. If making a gift of cash by check close to the end of the calendar year, the check should be cashed before December 31. The gift will not be complete during the time you can stop payment on your check. It is best not to create uncertainty. If making a cash gift right at the end of the year, to avoid any question as to when the gift is complete, consider using a certified check, bank check or, perhaps, a prepaid gift card.
A gift must be of a “present interest in property” to qualify for this exclusion from the gift tax. These are gifts that the beneficiary can access and use immediately.
A gift in trust that benefits the beneficiary only if a trustee makes a distribution from the trust cannot be readily accessed and is not a present interest in property.
Nevertheless, some gifts in trusts can qualify for the annual exclusion, as described below.
· Minor’s Trust under Section 2503(c): Gifts to a minor’s trusts created for a beneficiary under the age of 21 pursuant to Internal Revenue Code §2503(c) will qualify for the annual exclusion. To qualify as a §2503(c) minor’s trust, prior to the beneficiary attaining age 21, distributions may be made only to the beneficiary, the beneficiary must be able to take all property from the trust at age 21, and if the beneficiary dies before attaining age 21, the value of the trust property must be included in the beneficiary’s gross estate either by being paid to the beneficiary’s estate or pursuant to a general power of appointment held by the beneficiary.
· “Crummey” Trust: Gifts to a so-called “Crummey” Trust, that allows the beneficiary (or an adult acting on a minor beneficiary’s behalf) to withdraw a gift to the trust for a limited time after the gift is made, will also qualify for the annual exclusion. Sometimes, depending on the value of the trust, the lapse of the beneficiary’s power to withdraw property from the trust could cause the beneficiary (even if the beneficiary is a minor) to make a taxable gift. Accordingly, care should be used when deciding when and how much of a beneficiary’s withdrawal right should lapse in any one year.
Gifts to grandchildren and more remote descendants could also cause the imposition of a generation-skipping transfer tax (GSTT). This is an additional tax imposed on gifts made to persons two or more generations below the transferor.
Outright gifts to a grandchild or more remote descendant up to the annual exclusion amount are nontaxable gifts and are generally not subject to the GSTT.
Gifts made to a trust for a grandchild do not qualify for this treatment unless the trust is for a grandchild or more remote descendant and during the life of such beneficiary, no portion of the corpus or income of the trust may be distributed to, or for the benefit of, any person other than the beneficiary, and if the trust does not terminate before the beneficiary dies, the assets of such trust will be includable in the beneficiary’s gross estate.
Always remember to consult your attorney and financial advisors when making gifts or creating trusts.
design sophisticated, customized plans that can help you achieve a careful balance of control and flexibility, shaping your family's future while responding to its changing needs. We can assist you with:
What Estate Planning Documents Do I Need and Why?
Many people assume having a will is sufficient, but estate planning is more than just preparing a will. An estate plan typically should, at a minimum, include both financial and health care powers of attorney, a Health Insurance Portability and Accountability Act of 1996 (HIPAA) waiver, and living will. While a will can provide for the disposition of your assets upon your death, it is not legally effective to deal with a variety of other situations that could arise during your lifetime, such as incapacity and the need for someone to make medical or legal decisions on your behalf.
In keeping with a goals-based approach, estate planning should incorporate an integrated approach to determine which documents may be necessary to accomplish your objectives.
The documents you may want to consider including in your plan are set out below.
A Will
A will is a legal document that allows you to direct the distribution of your property following your death. Without a will your state’s intestacy statute will dictate who receives your property (which may not reflect how you want your assets to be distributed). For example, do you want a child to receive a large sum of money at age 18? What if you have a child or a spouse with special needs? Do you want an estranged family member with whom you have no relationship to receive assets that you have earmarked for a child or other beneficiaries?
In addition, a will gives you the ability to appoint a guardian for your minor children. Although the ultimate decision as to the appointment of a guardian rests with the appropriate court, by appointing a guardian in your will, you provide the judge with your preferences and may minimize the possibility of family conflict over who should care for your children. When choosing a guardian, you may want to consider not only those willing and qualified to take the job, but individuals who share your values and way of life.
Further, a will allows you to appoint an executor to oversee the distribution of your assets — the person who will be charged with carrying out your wishes when you are not here to do so yourself. You may want to keep in mind that acting as an executor is not an honor; rather, it is a job which requires completion of critical duties. Before you choose an executor (also known as a personal representative), you may want to weigh not only the qualifications of the individual but whether they have the time to devote to the numerous legal and tax duties required of the position. For many, appointing an individual as personal representative together with an institution can provide the right balance of technical experience and familial context.
Financial Power of Attorney
If you own any assets or property in your own name, you may wish to create a financial power of attorney. When you own an asset in your own name (for example, real estate, a bank account, or an investment account), only you have authority over this asset. If you are unable to make decisions regarding your assets, you may need to delegate authority to someone else to handle those assets should the need arise.
A financial power of attorney appoints an individual, commonly referred to as your “agent,” to handle your financial affairs should you become incapacitated or unable to handle day-to-day decision making.
Your agent will be able to act on your behalf by paying your bills, making investment decisions, handling tax and real estate matters, depositing money, and transacting other personal business you would otherwise have handled yourself. Without such a document, it may be necessary for a court to appoint someone on your behalf to handle these matters. Generally speaking, many people would prefer to choose who will make these decisions for them should the need arise rather than having a court make that choice. A financial power of attorney gives you that ability.
When Your Children Become Adults
Once a child attains the age of 18, the child is an adult and a parent can no longer access their medical records or make medical decisions on their behalf without special legal documents. A health care power of attorney naming someone (presumably the parent(s)) as a child’s medical agent will give the named individual(s) the ability to make medical decisions on behalf of the child should the child be unable to do so for themselves. Think about how it would be if you, as a parent, were not able to give or refuse consent for treatment or be able to gain access to medical information.
A HIPAA authorization is another “must have” document for college-aged children. A form signed by your child will permit you to receive information from health care providers about the child’s health and treatment.
Health Care Power of Attorney
Much like a financial power of attorney, a health care power of attorney allows you to designate someone (your agent) to make medical decisions for you should you be unable to make them for yourself.
If you are over the age of 18 and do not have a health care power of attorney, if you are incapacitated a petition will need to be filed with the appropriate court and a judge will appoint a guardian to make you health care decisions. Potentially, this could lead to unnecessary cost and delay which may be avoidable with the correct documents. Again, would you prefer a stranger to make these decisions, or would you rather determine who will have this ability.
A Living Will
If you are over 18 years of age, you may want to create a living will. A living will, also known as an advance health care directive, allows you to specify what end-of-life treatment you do or do not want to receive if you become terminally ill or permanently unconscious and will not survive without the administration of life support. A living will takes the decision to remove life support out of the hands of family members during a very emotional time by stating your wishes in advance.
HIPAA Waiver
If you are over the age of 18, you may want a HIPAA Waiver. While your health care power of attorney and advance health care directive will likely contain language that allows your agent to access your medical records, it is not uncommon for medical facilities to refuse access to medical information without a stand-alone HIPAA waiver. This back up document allows your family members to have access to your medical information so they can speak freely with your health care providers in case of a medical emergency or your incapacity.
If I Already Have Estate Planning Documents, Do I Need to Do Anything?
Your estate planning documents may be the most important documents you will ever write. Often though, after being executed, they are put away for safekeeping and not looked at again. That can be a mistake. You may want to review your plan regularly as your life evolves to determine if your documents still accurately reflect your goals. For example, consider the following common, but important, reasons for contemplating updates to your existing documents:
Next Steps – Create your ICE Pack (In Case of Emergency)
Remember, even the most carefully drafted documents will be of no value if your loved ones do not know where they are located. Consider creating the following, in case an emergency arises.
1. A folder containing copies of your estate planning documents, which someone knows how to find.
2. A special envelope containing your health care documents that is easily accessible should you need to be hospitalized. You may also want to have a copy of your Health Care Directive/Living Will on file with your personal physician and local hospital.
3. Lists of important information for your loved ones to easily access:
· Relevant personal contacts who should be notified in the case of an emergency.
· Assets, debts, expenses, account information, health care and life insurance documentation, as well as other important information should your designated agent, under either a financial or health care power of attorney, need to act on your behalf.
· Online accounts and their usernames/ passwords so that electronically stored photos, videos, email and social media accounts, as well as online accounts with various financial institutions, can be accessed.
· Medical history, medications, and health issues for your health care power of attorney agent(s). Also, do not overlook the importance of having a conversation with your designated agent regarding your wishes.
Finally, do the individuals named in your documents know you have chosen them to serve in a fiduciary capacity? Before you name someone to take on any of these responsibilities, it is important to discuss this with them beforehand.
Conclusion
In these uncertain times, being proactive by putting appropriate and up-to-date estate planning documents in place can help alleviate stress and create a measure of certainty and peace of mind that will serve you and your family well in the years to come. Your PNC Private Bank® team is here and ready to work with you and your advisors.
When to Review Your Will – Checklist
In addition to regularly reviewing your will and estate planning documents every three to five years, you should also consider reviewing your estate plan when these situations and life events arise:
· Upon birth or adoption of a child, grandchild, or other family member
· Following a marriage or divorce
· When someone named in your will passes away
· When a child or grandchild needs educational funding
· When children, grandchildren, or other heirs reach adulthood
· Upon changes in your executor’s, guardian’s, and/or trustee’s circumstances
· When the value of your estate significantly increases or decreases
· The acquisition or disposition of a significant asset
· Upon starting a business or when contemplating the transfer of a business
· Following changes in tax laws
· When you are approaching age 72 (the age when you are required to begin taking distributions from your individual retirement account, 401(k), or other qualified plan)
· After a move to a different state
· If you are diagnosed with a chronic or terminal illness or disability
Planning Using Powers of Appointment
Through the years, the dynamics of your family will change. Your family may grow, children and grandchildren may be born, some offspring may mature into wise adults and some may not, some family members may suffer through illness (perhaps debilitating), and, at some point, every member of the family will die. Of course, changes come from outside of your family, too. Tax and property laws change from one Congress to the next. Unanticipated events occur in the economy or in the financial markets. Businesses may succeed wildly or fail spectacularly.
Given the inevitable changes over the course of a lifetime, you may ask:
· Can I create an estate plan that may be later adjusted for the inevitable changes of life?
· If I plan for today’s circumstances, is it possible to also plan for an uncertain future – even for events that occur after I have departed this life when my estate plan becomes irrevocable?
· Can I plan now to protect my family’s wealth for generations to come, while allowing the plan to take into consideration changed circumstances?
The answer to each of the foregoing questions is yes.
Indeed, it is possible to secure your wealth for future generations yet provide for an uncertain future, no matter what comes, by building flexibility into the plan documents.
While there are many ways to build flexibility into the irrevocable documents that create your plan, using a power of appointment makes your plan flexible by allowing future generations to adapt it to later circumstances.
What is a Power of Appointment?
An important part of any wealth plan is the transfer of wealth from members of senior generations to members of junior generations. Of course, your plan can give property outright to any person. However, doing so fails to protect that property from many risks. Property owned by an individual outright may be disposed of in any manner by such person. Property transferred outright is “unprotected” because it is subject to the claims of the owner’s creditors (possibly including those of a divorcing spouse), it may be invested imprudently and lost and it can be given away, including to persons outside your family. To protect your wealth from those and other circumstances, instead of giving your wealth to your beneficiaries outright, you could create trusts for their benefit. In fact, to protect your property for long periods of time, you can create trusts that last for (and benefit) many generations of your descendants. (Note that some states have laws that require trusts to end by a certain date.[1] Check with your attorney to see how the laws of your state could impact your plan.)
Irrevocable trusts for your beneficiaries are generally governed by the terms that you set when you create the trust. As trust law has developed, however, many states have adopted laws that allow irrevocable trusts to be changed. These laws include judicial modifications (when a court changes a trust), non-judicial settlements (when the beneficiaries and trustees agree to change the terms of a trust) and decanting (when the trustee exercises a power in its discretion to distribute the trust to another trust). Additionally, the terms of your trust can give your beneficiaries the ability to change the terms of the trust by conferring upon them a power of appointment.
A “power of appointment” is a right that the creator of a trust[2] (the donor) confers upon another person (the donee or power holder) to direct the disposition of specified property. The donor of the power of appointment sets the terms as to how the power can be exercised and the steps that the holder of the power must follow to exercise the power. If the power holder does not comply with the requirements of the power of appointment, its exercise could be void.
For example, a power of appointment may:
· be exercisable immediately, or at some time in the future (such as when its holder dies);
· restrict who may receive property when the power is exercised (such as limiting recipients to the donor’s descendants);
· set conditions on what the beneficiaries receive and how they receive it, such as requiring the power to be exercised to create another trust (and not transfer property outright); or
· restrict the mechanism for exercising the power (for example, by only allowing it to be exercised by the power holder’s will and by specific reference to the document creating the power of appointment).
Types of Powers of Appointment
Powers of appointment can be customized to suit your circumstances as well as those of your family.
However, for federal gift and estate tax (collectively, transfer tax) purposes, there are two types of powers of appointment:[3] a general power of appointment and a limited power of appointment.
· A general power of appointment allows the power holder to direct property to be distributed to any person or entity and subject to any condition as specified in the power of appointment, but the power holder must also have the ability to direct the property to be distributed to any of (i) the power holder, (ii) the power holder’s creditors, (iii) the power holder’s estate or (iv) the creditors of the power holder’s estate.[4]
· A limited power of appointment (also known as a special power of appointment) allows the power holder to direct the property to be distributed to any person or entity and subject to any condition as specified in the power of appointment other than (i) the power holder, (ii) the power holder’s creditors, (iii) the power holder’s estate or (iv) the creditors of the power holder’s estate. A limited power of appointment can be quite broad, as it can be drafted to allow the power holder to appoint the property subject to the power to anyone or any entity in the world other than the four above stated exceptions.
Ownership and Powers of Appointment
With limited exceptions, state law creates and governs interests in property and ownership rights.[5] The power holder must look to state law to determine what is owned and the rights conferred by such ownership. For example, a presently exercisable general power of appointment in favor of the power holder allows the power holder to “take” the property subject to the power of appointment. Such a power is the legal equivalent of ownership and subjects the property subject to the power of appointment to the claims of the power holder’s creditors. However, a general power of appointment exercisable by will may not be subject to the claims of the power holder’s creditors during life but could be subject to the power holder’s creditors at death. Conversely, a limited power of appointment (whether exercisable during life or at death) does not confer any economic benefit on the power holder and is not subject to the claims of the power holder’s creditors.[6] As the law of each state is different, you should consult with your attorney to determine ownership rights.
Tax Treatment of Powers of Appointment
Powers of appointment can have important tax consequences to the power holder. Generally, if the power holder dies holding a general power of appointment created after October 21, 1942 (whether the power of appointment is exercised or not), the value of the property subject to the power will be included in the power holder’s gross estate and potentially subject to federal estate tax.[7] The value of the property subject to a general power of appointment would also be included in the power holder’s gross estate if the power holder released or exercised the power under circumstances such that, had the power holder owned and transferred the property subject to the power of appointment, the property would be includible in the deceased power holder’s gross estate under certain other sections of the Internal Revenue Code (IRC).[8]
On the other hand, the value of property subject to a limited power of appointment will not be included in the power holder’s gross estate at death unless the power holder exercises the original power of appointment to
· create a second power of appointment, and
· the second power of appointment can be exercised to prevent the property subject to the second power from being owned outright or being transferred, and
· the period of time during which the property cannot be owned outright or transferred does not reference the date the original power was created.[9]
For gift tax purposes, the exercise or release of a general power of appointment created after October 21, 1942, will be deemed a transfer of property by the power holder and potentially subject to gift tax, unless the value of the property subject to the power that lapses or is released is less than the greater of $5,000 or 5% of the total value of the property subject to the power of appointment.[10]
For income tax purposes:
· to the extent property is included in the gross estate of the power holder, its tax cost basis will become its fair market value at death. The basis of appreciated property will “step up” to its then-fair market value, whereas the basis of depreciated property will be “stepped down.”
· in some cases a trust beneficiary who holds a presently exercisable power of appointment allowing the beneficiary to take the property in a trust (or who had such a power that has lapsed but has certain rights over the trust) can be treated as owning the property in the trust for income tax purposes (making the trust a so-called grantor trust).[11]
Using Powers of Appointment
As circumstances change, powers of appointment can provide flexibility to your plan. There are many ways to use powers of appointment to the advantage of your family. Following are some examples.
As circumstances change, powers of appointment can provide flexibility to your plan. There are many ways to use powers of appointment to the advantage of your family.
Unexpected Problems Arise After Death
Planning for Changed Circumstances
Spouse 1 dies, leaving a trust for the benefit of Spouse 2. The trust requires that its income be paid to Spouse 2 at least annually for life and gives the trustee the discretion to distribute principal to Spouse 2. Spouse 2 also is granted a limited power of appointment to direct the trust property to be distributed outright or in further trust for any of the Spouse 1’s descendants at Spouse 2’s death. If the power is not exercised, the assets remaining in the trust will be distributed outright to the descendants of Spouse 1, per stirpes. Assume that Spouse 1 has two children. Further assume that the oldest child of Spouse 1 develops a substance abuse problem after Spouse 1 died.
Upon Spouse 2’s death, if nothing is done, each of the children would receive one-half of the trust property, outright. In that case, property received by the older child could perpetuate, or even exacerbate, the substance abuse issues. Instead, Spouse 2 could exercise the power of appointment, requiring the oldest child’s share to be held in a trust, to provide for that child (even to the point of paying for treatment). The oldest child’s share would be protected from that child’s potential improvidence, shielded from that child’s creditors and available to care for that child. Moreover, the property would be unavailable to feed that child’s self-destructive behavior.
Special Needs
Using the same facts as outlined above, assume that after Spouse 1 died, the younger child has a child (grandchild) with severe disabilities who will require professional care for life. If the grandchild were to receive property from the trust, such a distribution could disqualify the grandchild from receiving public assistance. Ignoring tax consequences for the moment, assume Spouse 2 and the younger child plan together that Spouse 2 should provide some funds to care for the grandchild upon Spouse 2’s death. In that case, Spouse 2 could exercise the power of appointment in such a way as to provide a trust that could be used in part for the younger child and in part to provide the grandchild with services and items not provided by government assistance. Further, the power could be exercised so that upon the younger child’s death, whatever property remained in the child’s trust would continue in a trust to provide the grandchild with services and items not provided by government assistance for the rest of grandchild’s life. Upon the grandchild’s subsequent death, if there is property remaining in the trust, the exercise of the power would specify which of the descendants of Spouse 1 would receive the property and the conditions upon which it would be received. For example, if the younger child had no other descendants, any remaining property could be added to the trust for the older child.
Financial Windfall
Assume the same facts as outlined above, except that the younger child has children (grandchildren), none of whom have special needs. Further assume that the younger child was a business owner who sold the business for hundreds of millions of dollars. If Spouse 2 takes no action, upon the death of Spouse 2 one-half of the trust would be paid outright to the younger child. This would augment younger child’s estate, which (based on current law) would be subject to a substantial estate tax. Ignoring taxes for the moment, because the younger child already has a large estate, perhaps Spouse 2 could exercise the power of appointment to create trusts for the grandchildren.
Limitations on Exercise
In each of the foregoing examples, because the power of appointment restricted the possible appointees to the descendants of Spouse 1, Spouse 2 could not have directed the trust to be distributed to anyone or any entity other than a descendant of Spouse 1. If the power of appointment had allowed trust assets to be distributed “to any person or entity other than Spouse 2, Spouse 2’s creditors, Spouse 2’s estate or the creditors of Spouse 2’s estate,” Spouse 2 could have directed the entire trust to be distributed to any person or entity (either outright or in trust) other than the four entities prohibited from receiving property. In that case, even though that power of appointment would still have been a limited power of appointment, the group of potential appointees would have been so broad that Spouse 2 could have caused the property to be distributed to virtually anyone, including a new spouse, the new spouse’s children or a charitable organization. Thus, great care should be taken when drafting powers of appointment to balance flexibility with the desire to keep wealth within the family.
Tax Planning with Powers of Appointment
Taxpayers create extensive plans to minimize their overall tax liabilities. As one of America’s great jurists once wrote: “Any one (sic) may so arrange his affairs that his taxes shall be as low as possible; he is not bound to choose that pattern which will best pay the Treasury; there is not even a patriotic duty to increase one’s taxes.”[12]
For decades, taxpayers have used trusts to minimize the amount of transfer taxes required to be paid by each generation of their families. Many of these strategies involve long-term trusts.
These trusts are designed to last for many generations, without being subject to transfer taxes. (Although beyond the scope of this article, usually the transferor has allocated exemption from the generation-skipping transfer tax to the trust so that it has an inclusion ratio of zero, or the trust was irrevocable before September 25, 1985.) This means that the terms of the trusts are crafted so that the value of the trust’s property is not included in the gross estate of any beneficiary who dies. The benefit of avoiding estate tax at each generation is illustrated by the table on page 5.
However, avoiding transfer taxes by holding property in a long-term trust may cause an income tax issue. As the assets in the trust appreciate, the unrealized capital gain in the assets grows. Because the assets of the trust are not considered to be transferred by the trust’s beneficiaries, the assets in the trust never receive a so-called basis step up as each beneficiary dies.[13]
In 2022, each citizen and resident of the United States has an exclusion from the federal estate tax of $12.06 million. This exclusion amount represents a significant increase from exclusion amounts of previous years. In fact, as late as 2002, the exclusion amount was only $1 million. As estate tax exclusion amounts have grown, fewer taxpayers have been subject to the federal estate tax.
Is it possible to both avoid transfer taxes and get a step-up in basis to reduce capital gain tax? To some extent, the answer is yes.
When creating a new estate plan, you could create trusts that optimize both transfer tax and capital gains tax savings. To do so, the terms of your trust could grant its beneficiaries a carefully crafted general power of appointment. Each beneficiary would have a general power of appointment (exercisable when the beneficiary dies) over an amount of property in the trust determined by a formula. The formula would limit the amount of property subject to the power of appointment to the beneficiary’s available (or unused) estate tax exclusion amount (so that no estate tax would be paid). Further, the formula would apply to those assets with the greatest unrealized capital gain. Thus, upon the beneficiary’s death, assuming the beneficiary has available estate tax exclusion, property of the trust equal in value to the unused exclusion amount with the greatest built-in capital gain would receive a step-up in basis, yet no estate tax would be due. Alternatively, the terms of the trust could designate a so-called trust protector who has the authority to confer a formulaic general power of appointment upon a beneficiary should the circumstances favor such a provision.
It may also be possible to modify an existing irrevocable trust to add a formulaic general power of appointment or add a trust protector who can confer general powers of appointment to take advantage of the technique described above. Depending on the state law governing the trust, it may be possible to modify the trust through judicial modification (when a court changes a trust), non-judicial settlement (when the beneficiaries and trustees agree to change the terms of a trust) and decanting (when the trustee exercises a power in its discretion to distribute the trust to another trust).
Still further, if the beneficiary already has been granted a limited power of appointment over the assets of the trust, depending on the state law governing the trust, it may be possible to exercise even a limited power of appointment to cause some or all of the trust’s assets to be subject to transfer tax when the beneficiary dies. To do this, the beneficiary would exercise the original power of appointment in a way that creates a second power of appointment so that second power of appointment can be exercised to prevent the property subject to the power from being owned by someone outright or being transferred for a period of time that does not reference the date upon which the original power of appointment was created.[14] This is colloquially known as “springing the Delaware tax trap.” Nevertheless, the laws of some states prevent the trap from being sprung. Before attempting to spring the Delaware tax trap, consult an attorney in the state whose law governs the trust.
* This hypothetical is for illustrative purposes only. Tax calculations have been simplified for illustrative purposes and do not take into account any tax attributes that may affect a taxpayer's particular situation (for example state and local taxes, marital status, or exemptions).
Table 1: Benefit of Avoiding Estate Tax by Generation*
Trust Not Exempt from Transfer Taxes
Year
1 (Creation)
50
100
150
200
Trust Property
$1,500,000
$10,660,025
$41,666,582
$162,861,163
$636,571,495
Estate/GSTT Tax
($4,797,011)
($18,749,962)
($73,287,524)
($286,457,173)
Balance in Trust
$1,500,000
$5,863,014
$22,916,620
$89,573,640
$350,114,322
Table 2: Benefit of Avoiding Estate Tax by Generation*
Trust Exempt from Transfer Taxes
Year
1 (Creation)
50
100
150
200
Trust Property
$1,500,000
$10,660,025
$75,757,422
$538,384,011
$3,826,124,687
Estate/GSTT Tax
$0
$0
$0
$0
Balance in Trust
$1,500,000
$10,660,025
$75,757,422
$538,384,011
$3,826,124,687
Benefit to Family
$0
$4,797,011
$52,840,802
$448,810,371
$3,476,010,365
A federal estate and/or generation-skipping transfer tax (GSTT). Tax is imposed every 50 years. The federal estate and/or GSTT Tax Rate is 40%. Trust property grows at 4% each year (after federal income tax).
A Flexible, but Complex, Tool
Powers of appointment are powerful planning tools. They can be included in your plan documents at the outset or, depending on applicable state law, added to the terms of an existing irrevocable trust through a modification.
Powers of appointment can be customized to fit your and your family’s particular circumstances. Adding a power of appointment to your plan provides your beneficiaries with the ability to alter the plan to fit changing circumstances.
However, because powers of appointment are powerful, customizable and can have a large impact on taxation, you should consult with your legal, tax and financial advisors when considering adding powers of appointment to a new plan or modifying an old plan to include them.
The annual exclusion amount permits donors to give without facing a gift tax. What should you consider in regards to annual exclusion gifting?
Jun 20 2023 | 3 min read
The federal government imposes a tax on gifts. However, Congress has permitted donors to give a small amount to each beneficiary of their choosing before facing the federal gift tax. This amount is known as the annual exclusion amount, which for 2023 is $17,000 per beneficiary.
The value of all gifts made during the year to a single beneficiary count towards the donor’s $17,000 annual exclusion, no matter what their form. Thus, if you give your child a $10,000 automobile, you have used $10,000 of your annual exclusion and have $7,000 left to give that child within the annual exclusion amount.
Special rules apply to married couples. Two spouses can “split” a gift to a single beneficiary and treat it as if one-half of the total was made by each spouse, no matter which spouse actually made the gift. This technique allows one spouse to make gifts using both spouses’ annual exclusions, for a total gift of $34,000. To qualify for gift splitting, the spouses must file federal gift tax returns signed by both spouses consenting to the split, even if a return would not otherwise be necessary were each to give $17,000 individually.
Your gift must be “complete” by year-end. If making a gift of cash by check close to the end of the calendar year, the check should be cashed before December 31. The gift will not be complete during the time you can stop payment on your check. It is best not to create uncertainty. If making a cash gift right at the end of the year, to avoid any question as to when the gift is complete, consider using a certified check, bank check or, perhaps, a prepaid gift card.
A gift must be of a “present interest in property” to qualify for this exclusion from the gift tax. These are gifts that the beneficiary can access and use immediately.
A gift in trust that benefits the beneficiary only if a trustee makes a distribution from the trust cannot be readily accessed and is not a present interest in property.
Nevertheless, some gifts in trusts can qualify for the annual exclusion, as described below.
· Minor’s Trust under Section 2503(c): Gifts to a minor’s trusts created for a beneficiary under the age of 21 pursuant to Internal Revenue Code §2503(c) will qualify for the annual exclusion. To qualify as a §2503(c) minor’s trust, prior to the beneficiary attaining age 21, distributions may be made only to the beneficiary, the beneficiary must be able to take all property from the trust at age 21, and if the beneficiary dies before attaining age 21, the value of the trust property must be included in the beneficiary’s gross estate either by being paid to the beneficiary’s estate or pursuant to a general power of appointment held by the beneficiary.
· “Crummey” Trust: Gifts to a so-called “Crummey” Trust, that allows the beneficiary (or an adult acting on a minor beneficiary’s behalf) to withdraw a gift to the trust for a limited time after the gift is made, will also qualify for the annual exclusion. Sometimes, depending on the value of the trust, the lapse of the beneficiary’s power to withdraw property from the trust could cause the beneficiary (even if the beneficiary is a minor) to make a taxable gift. Accordingly, care should be used when deciding when and how much of a beneficiary’s withdrawal right should lapse in any one year.
Gifts to grandchildren and more remote descendants could also cause the imposition of a generation-skipping transfer tax (GSTT). This is an additional tax imposed on gifts made to persons two or more generations below the transferor.
Outright gifts to a grandchild or more remote descendant up to the annual exclusion amount are nontaxable gifts and are generally not subject to the GSTT.
Gifts made to a trust for a grandchild do not qualify for this treatment unless the trust is for a grandchild or more remote descendant and during the life of such beneficiary, no portion of the corpus or income of the trust may be distributed to, or for the benefit of, any person other than the beneficiary, and if the trust does not terminate before the beneficiary dies, the assets of such trust will be includable in the beneficiary’s gross estate.
Always remember to consult your attorney and financial advisors when making gifts or creating trusts.
design sophisticated, customized plans that can help you achieve a careful balance of control and flexibility, shaping your family's future while responding to its changing needs. We can assist you with:
What Estate Planning Documents Do I Need and Why?
Many people assume having a will is sufficient, but estate planning is more than just preparing a will. An estate plan typically should, at a minimum, include both financial and health care powers of attorney, a Health Insurance Portability and Accountability Act of 1996 (HIPAA) waiver, and living will. While a will can provide for the disposition of your assets upon your death, it is not legally effective to deal with a variety of other situations that could arise during your lifetime, such as incapacity and the need for someone to make medical or legal decisions on your behalf.
In keeping with a goals-based approach, estate planning should incorporate an integrated approach to determine which documents may be necessary to accomplish your objectives.
The documents you may want to consider including in your plan are set out below.
A Will
A will is a legal document that allows you to direct the distribution of your property following your death. Without a will your state’s intestacy statute will dictate who receives your property (which may not reflect how you want your assets to be distributed). For example, do you want a child to receive a large sum of money at age 18? What if you have a child or a spouse with special needs? Do you want an estranged family member with whom you have no relationship to receive assets that you have earmarked for a child or other beneficiaries?
In addition, a will gives you the ability to appoint a guardian for your minor children. Although the ultimate decision as to the appointment of a guardian rests with the appropriate court, by appointing a guardian in your will, you provide the judge with your preferences and may minimize the possibility of family conflict over who should care for your children. When choosing a guardian, you may want to consider not only those willing and qualified to take the job, but individuals who share your values and way of life.
Further, a will allows you to appoint an executor to oversee the distribution of your assets — the person who will be charged with carrying out your wishes when you are not here to do so yourself. You may want to keep in mind that acting as an executor is not an honor; rather, it is a job which requires completion of critical duties. Before you choose an executor (also known as a personal representative), you may want to weigh not only the qualifications of the individual but whether they have the time to devote to the numerous legal and tax duties required of the position. For many, appointing an individual as personal representative together with an institution can provide the right balance of technical experience and familial context.
Financial Power of Attorney
If you own any assets or property in your own name, you may wish to create a financial power of attorney. When you own an asset in your own name (for example, real estate, a bank account, or an investment account), only you have authority over this asset. If you are unable to make decisions regarding your assets, you may need to delegate authority to someone else to handle those assets should the need arise.
A financial power of attorney appoints an individual, commonly referred to as your “agent,” to handle your financial affairs should you become incapacitated or unable to handle day-to-day decision making.
Your agent will be able to act on your behalf by paying your bills, making investment decisions, handling tax and real estate matters, depositing money, and transacting other personal business you would otherwise have handled yourself. Without such a document, it may be necessary for a court to appoint someone on your behalf to handle these matters. Generally speaking, many people would prefer to choose who will make these decisions for them should the need arise rather than having a court make that choice. A financial power of attorney gives you that ability.
When Your Children Become Adults
Once a child attains the age of 18, the child is an adult and a parent can no longer access their medical records or make medical decisions on their behalf without special legal documents. A health care power of attorney naming someone (presumably the parent(s)) as a child’s medical agent will give the named individual(s) the ability to make medical decisions on behalf of the child should the child be unable to do so for themselves. Think about how it would be if you, as a parent, were not able to give or refuse consent for treatment or be able to gain access to medical information.
A HIPAA authorization is another “must have” document for college-aged children. A form signed by your child will permit you to receive information from health care providers about the child’s health and treatment.
Health Care Power of Attorney
Much like a financial power of attorney, a health care power of attorney allows you to designate someone (your agent) to make medical decisions for you should you be unable to make them for yourself.
If you are over the age of 18 and do not have a health care power of attorney, if you are incapacitated a petition will need to be filed with the appropriate court and a judge will appoint a guardian to make you health care decisions. Potentially, this could lead to unnecessary cost and delay which may be avoidable with the correct documents. Again, would you prefer a stranger to make these decisions, or would you rather determine who will have this ability.
A Living Will
If you are over 18 years of age, you may want to create a living will. A living will, also known as an advance health care directive, allows you to specify what end-of-life treatment you do or do not want to receive if you become terminally ill or permanently unconscious and will not survive without the administration of life support. A living will takes the decision to remove life support out of the hands of family members during a very emotional time by stating your wishes in advance.
HIPAA Waiver
If you are over the age of 18, you may want a HIPAA Waiver. While your health care power of attorney and advance health care directive will likely contain language that allows your agent to access your medical records, it is not uncommon for medical facilities to refuse access to medical information without a stand-alone HIPAA waiver. This back up document allows your family members to have access to your medical information so they can speak freely with your health care providers in case of a medical emergency or your incapacity.
If I Already Have Estate Planning Documents, Do I Need to Do Anything?
Your estate planning documents may be the most important documents you will ever write. Often though, after being executed, they are put away for safekeeping and not looked at again. That can be a mistake. You may want to review your plan regularly as your life evolves to determine if your documents still accurately reflect your goals. For example, consider the following common, but important, reasons for contemplating updates to your existing documents:
Next Steps – Create your ICE Pack (In Case of Emergency)
Remember, even the most carefully drafted documents will be of no value if your loved ones do not know where they are located. Consider creating the following, in case an emergency arises.
1. A folder containing copies of your estate planning documents, which someone knows how to find.
2. A special envelope containing your health care documents that is easily accessible should you need to be hospitalized. You may also want to have a copy of your Health Care Directive/Living Will on file with your personal physician and local hospital.
3. Lists of important information for your loved ones to easily access:
· Relevant personal contacts who should be notified in the case of an emergency.
· Assets, debts, expenses, account information, health care and life insurance documentation, as well as other important information should your designated agent, under either a financial or health care power of attorney, need to act on your behalf.
· Online accounts and their usernames/ passwords so that electronically stored photos, videos, email and social media accounts, as well as online accounts with various financial institutions, can be accessed.
· Medical history, medications, and health issues for your health care power of attorney agent(s). Also, do not overlook the importance of having a conversation with your designated agent regarding your wishes.
Finally, do the individuals named in your documents know you have chosen them to serve in a fiduciary capacity? Before you name someone to take on any of these responsibilities, it is important to discuss this with them beforehand.
Conclusion
In these uncertain times, being proactive by putting appropriate and up-to-date estate planning documents in place can help alleviate stress and create a measure of certainty and peace of mind that will serve you and your family well in the years to come. Your PNC Private Bank® team is here and ready to work with you and your advisors.
When to Review Your Will – Checklist
In addition to regularly reviewing your will and estate planning documents every three to five years, you should also consider reviewing your estate plan when these situations and life events arise:
· Upon birth or adoption of a child, grandchild, or other family member
· Following a marriage or divorce
· When someone named in your will passes away
· When a child or grandchild needs educational funding
· When children, grandchildren, or other heirs reach adulthood
· Upon changes in your executor’s, guardian’s, and/or trustee’s circumstances
· When the value of your estate significantly increases or decreases
· The acquisition or disposition of a significant asset
· Upon starting a business or when contemplating the transfer of a business
· Following changes in tax laws
· When you are approaching age 72 (the age when you are required to begin taking distributions from your individual retirement account, 401(k), or other qualified plan)
· After a move to a different state
· If you are diagnosed with a chronic or terminal illness or disability
Planning Using Powers of Appointment
Through the years, the dynamics of your family will change. Your family may grow, children and grandchildren may be born, some offspring may mature into wise adults and some may not, some family members may suffer through illness (perhaps debilitating), and, at some point, every member of the family will die. Of course, changes come from outside of your family, too. Tax and property laws change from one Congress to the next. Unanticipated events occur in the economy or in the financial markets. Businesses may succeed wildly or fail spectacularly.
Given the inevitable changes over the course of a lifetime, you may ask:
· Can I create an estate plan that may be later adjusted for the inevitable changes of life?
· If I plan for today’s circumstances, is it possible to also plan for an uncertain future – even for events that occur after I have departed this life when my estate plan becomes irrevocable?
· Can I plan now to protect my family’s wealth for generations to come, while allowing the plan to take into consideration changed circumstances?
The answer to each of the foregoing questions is yes.
Indeed, it is possible to secure your wealth for future generations yet provide for an uncertain future, no matter what comes, by building flexibility into the plan documents.
While there are many ways to build flexibility into the irrevocable documents that create your plan, using a power of appointment makes your plan flexible by allowing future generations to adapt it to later circumstances.
What is a Power of Appointment?
An important part of any wealth plan is the transfer of wealth from members of senior generations to members of junior generations. Of course, your plan can give property outright to any person. However, doing so fails to protect that property from many risks. Property owned by an individual outright may be disposed of in any manner by such person. Property transferred outright is “unprotected” because it is subject to the claims of the owner’s creditors (possibly including those of a divorcing spouse), it may be invested imprudently and lost and it can be given away, including to persons outside your family. To protect your wealth from those and other circumstances, instead of giving your wealth to your beneficiaries outright, you could create trusts for their benefit. In fact, to protect your property for long periods of time, you can create trusts that last for (and benefit) many generations of your descendants. (Note that some states have laws that require trusts to end by a certain date.[1] Check with your attorney to see how the laws of your state could impact your plan.)
Irrevocable trusts for your beneficiaries are generally governed by the terms that you set when you create the trust. As trust law has developed, however, many states have adopted laws that allow irrevocable trusts to be changed. These laws include judicial modifications (when a court changes a trust), non-judicial settlements (when the beneficiaries and trustees agree to change the terms of a trust) and decanting (when the trustee exercises a power in its discretion to distribute the trust to another trust). Additionally, the terms of your trust can give your beneficiaries the ability to change the terms of the trust by conferring upon them a power of appointment.
A “power of appointment” is a right that the creator of a trust[2] (the donor) confers upon another person (the donee or power holder) to direct the disposition of specified property. The donor of the power of appointment sets the terms as to how the power can be exercised and the steps that the holder of the power must follow to exercise the power. If the power holder does not comply with the requirements of the power of appointment, its exercise could be void.
For example, a power of appointment may:
· be exercisable immediately, or at some time in the future (such as when its holder dies);
· restrict who may receive property when the power is exercised (such as limiting recipients to the donor’s descendants);
· set conditions on what the beneficiaries receive and how they receive it, such as requiring the power to be exercised to create another trust (and not transfer property outright); or
· restrict the mechanism for exercising the power (for example, by only allowing it to be exercised by the power holder’s will and by specific reference to the document creating the power of appointment).
Types of Powers of Appointment
Powers of appointment can be customized to suit your circumstances as well as those of your family.
However, for federal gift and estate tax (collectively, transfer tax) purposes, there are two types of powers of appointment:[3] a general power of appointment and a limited power of appointment.
· A general power of appointment allows the power holder to direct property to be distributed to any person or entity and subject to any condition as specified in the power of appointment, but the power holder must also have the ability to direct the property to be distributed to any of (i) the power holder, (ii) the power holder’s creditors, (iii) the power holder’s estate or (iv) the creditors of the power holder’s estate.[4]
· A limited power of appointment (also known as a special power of appointment) allows the power holder to direct the property to be distributed to any person or entity and subject to any condition as specified in the power of appointment other than (i) the power holder, (ii) the power holder’s creditors, (iii) the power holder’s estate or (iv) the creditors of the power holder’s estate. A limited power of appointment can be quite broad, as it can be drafted to allow the power holder to appoint the property subject to the power to anyone or any entity in the world other than the four above stated exceptions.
Ownership and Powers of Appointment
With limited exceptions, state law creates and governs interests in property and ownership rights.[5] The power holder must look to state law to determine what is owned and the rights conferred by such ownership. For example, a presently exercisable general power of appointment in favor of the power holder allows the power holder to “take” the property subject to the power of appointment. Such a power is the legal equivalent of ownership and subjects the property subject to the power of appointment to the claims of the power holder’s creditors. However, a general power of appointment exercisable by will may not be subject to the claims of the power holder’s creditors during life but could be subject to the power holder’s creditors at death. Conversely, a limited power of appointment (whether exercisable during life or at death) does not confer any economic benefit on the power holder and is not subject to the claims of the power holder’s creditors.[6] As the law of each state is different, you should consult with your attorney to determine ownership rights.
Tax Treatment of Powers of Appointment
Powers of appointment can have important tax consequences to the power holder. Generally, if the power holder dies holding a general power of appointment created after October 21, 1942 (whether the power of appointment is exercised or not), the value of the property subject to the power will be included in the power holder’s gross estate and potentially subject to federal estate tax.[7] The value of the property subject to a general power of appointment would also be included in the power holder’s gross estate if the power holder released or exercised the power under circumstances such that, had the power holder owned and transferred the property subject to the power of appointment, the property would be includible in the deceased power holder’s gross estate under certain other sections of the Internal Revenue Code (IRC).[8]
On the other hand, the value of property subject to a limited power of appointment will not be included in the power holder’s gross estate at death unless the power holder exercises the original power of appointment to
· create a second power of appointment, and
· the second power of appointment can be exercised to prevent the property subject to the second power from being owned outright or being transferred, and
· the period of time during which the property cannot be owned outright or transferred does not reference the date the original power was created.[9]
For gift tax purposes, the exercise or release of a general power of appointment created after October 21, 1942, will be deemed a transfer of property by the power holder and potentially subject to gift tax, unless the value of the property subject to the power that lapses or is released is less than the greater of $5,000 or 5% of the total value of the property subject to the power of appointment.[10]
For income tax purposes:
· to the extent property is included in the gross estate of the power holder, its tax cost basis will become its fair market value at death. The basis of appreciated property will “step up” to its then-fair market value, whereas the basis of depreciated property will be “stepped down.”
· in some cases a trust beneficiary who holds a presently exercisable power of appointment allowing the beneficiary to take the property in a trust (or who had such a power that has lapsed but has certain rights over the trust) can be treated as owning the property in the trust for income tax purposes (making the trust a so-called grantor trust).[11]
Using Powers of Appointment
As circumstances change, powers of appointment can provide flexibility to your plan. There are many ways to use powers of appointment to the advantage of your family. Following are some examples.
As circumstances change, powers of appointment can provide flexibility to your plan. There are many ways to use powers of appointment to the advantage of your family.
Unexpected Problems Arise After Death
Planning for Changed Circumstances
Spouse 1 dies, leaving a trust for the benefit of Spouse 2. The trust requires that its income be paid to Spouse 2 at least annually for life and gives the trustee the discretion to distribute principal to Spouse 2. Spouse 2 also is granted a limited power of appointment to direct the trust property to be distributed outright or in further trust for any of the Spouse 1’s descendants at Spouse 2’s death. If the power is not exercised, the assets remaining in the trust will be distributed outright to the descendants of Spouse 1, per stirpes. Assume that Spouse 1 has two children. Further assume that the oldest child of Spouse 1 develops a substance abuse problem after Spouse 1 died.
Upon Spouse 2’s death, if nothing is done, each of the children would receive one-half of the trust property, outright. In that case, property received by the older child could perpetuate, or even exacerbate, the substance abuse issues. Instead, Spouse 2 could exercise the power of appointment, requiring the oldest child’s share to be held in a trust, to provide for that child (even to the point of paying for treatment). The oldest child’s share would be protected from that child’s potential improvidence, shielded from that child’s creditors and available to care for that child. Moreover, the property would be unavailable to feed that child’s self-destructive behavior.
Special Needs
Using the same facts as outlined above, assume that after Spouse 1 died, the younger child has a child (grandchild) with severe disabilities who will require professional care for life. If the grandchild were to receive property from the trust, such a distribution could disqualify the grandchild from receiving public assistance. Ignoring tax consequences for the moment, assume Spouse 2 and the younger child plan together that Spouse 2 should provide some funds to care for the grandchild upon Spouse 2’s death. In that case, Spouse 2 could exercise the power of appointment in such a way as to provide a trust that could be used in part for the younger child and in part to provide the grandchild with services and items not provided by government assistance. Further, the power could be exercised so that upon the younger child’s death, whatever property remained in the child’s trust would continue in a trust to provide the grandchild with services and items not provided by government assistance for the rest of grandchild’s life. Upon the grandchild’s subsequent death, if there is property remaining in the trust, the exercise of the power would specify which of the descendants of Spouse 1 would receive the property and the conditions upon which it would be received. For example, if the younger child had no other descendants, any remaining property could be added to the trust for the older child.
Financial Windfall
Assume the same facts as outlined above, except that the younger child has children (grandchildren), none of whom have special needs. Further assume that the younger child was a business owner who sold the business for hundreds of millions of dollars. If Spouse 2 takes no action, upon the death of Spouse 2 one-half of the trust would be paid outright to the younger child. This would augment younger child’s estate, which (based on current law) would be subject to a substantial estate tax. Ignoring taxes for the moment, because the younger child already has a large estate, perhaps Spouse 2 could exercise the power of appointment to create trusts for the grandchildren.
Limitations on Exercise
In each of the foregoing examples, because the power of appointment restricted the possible appointees to the descendants of Spouse 1, Spouse 2 could not have directed the trust to be distributed to anyone or any entity other than a descendant of Spouse 1. If the power of appointment had allowed trust assets to be distributed “to any person or entity other than Spouse 2, Spouse 2’s creditors, Spouse 2’s estate or the creditors of Spouse 2’s estate,” Spouse 2 could have directed the entire trust to be distributed to any person or entity (either outright or in trust) other than the four entities prohibited from receiving property. In that case, even though that power of appointment would still have been a limited power of appointment, the group of potential appointees would have been so broad that Spouse 2 could have caused the property to be distributed to virtually anyone, including a new spouse, the new spouse’s children or a charitable organization. Thus, great care should be taken when drafting powers of appointment to balance flexibility with the desire to keep wealth within the family.
Tax Planning with Powers of Appointment
Taxpayers create extensive plans to minimize their overall tax liabilities. As one of America’s great jurists once wrote: “Any one (sic) may so arrange his affairs that his taxes shall be as low as possible; he is not bound to choose that pattern which will best pay the Treasury; there is not even a patriotic duty to increase one’s taxes.”[12]
For decades, taxpayers have used trusts to minimize the amount of transfer taxes required to be paid by each generation of their families. Many of these strategies involve long-term trusts.
These trusts are designed to last for many generations, without being subject to transfer taxes. (Although beyond the scope of this article, usually the transferor has allocated exemption from the generation-skipping transfer tax to the trust so that it has an inclusion ratio of zero, or the trust was irrevocable before September 25, 1985.) This means that the terms of the trusts are crafted so that the value of the trust’s property is not included in the gross estate of any beneficiary who dies. The benefit of avoiding estate tax at each generation is illustrated by the table on page 5.
However, avoiding transfer taxes by holding property in a long-term trust may cause an income tax issue. As the assets in the trust appreciate, the unrealized capital gain in the assets grows. Because the assets of the trust are not considered to be transferred by the trust’s beneficiaries, the assets in the trust never receive a so-called basis step up as each beneficiary dies.[13]
In 2022, each citizen and resident of the United States has an exclusion from the federal estate tax of $12.06 million. This exclusion amount represents a significant increase from exclusion amounts of previous years. In fact, as late as 2002, the exclusion amount was only $1 million. As estate tax exclusion amounts have grown, fewer taxpayers have been subject to the federal estate tax.
Is it possible to both avoid transfer taxes and get a step-up in basis to reduce capital gain tax? To some extent, the answer is yes.
When creating a new estate plan, you could create trusts that optimize both transfer tax and capital gains tax savings. To do so, the terms of your trust could grant its beneficiaries a carefully crafted general power of appointment. Each beneficiary would have a general power of appointment (exercisable when the beneficiary dies) over an amount of property in the trust determined by a formula. The formula would limit the amount of property subject to the power of appointment to the beneficiary’s available (or unused) estate tax exclusion amount (so that no estate tax would be paid). Further, the formula would apply to those assets with the greatest unrealized capital gain. Thus, upon the beneficiary’s death, assuming the beneficiary has available estate tax exclusion, property of the trust equal in value to the unused exclusion amount with the greatest built-in capital gain would receive a step-up in basis, yet no estate tax would be due. Alternatively, the terms of the trust could designate a so-called trust protector who has the authority to confer a formulaic general power of appointment upon a beneficiary should the circumstances favor such a provision.
It may also be possible to modify an existing irrevocable trust to add a formulaic general power of appointment or add a trust protector who can confer general powers of appointment to take advantage of the technique described above. Depending on the state law governing the trust, it may be possible to modify the trust through judicial modification (when a court changes a trust), non-judicial settlement (when the beneficiaries and trustees agree to change the terms of a trust) and decanting (when the trustee exercises a power in its discretion to distribute the trust to another trust).
Still further, if the beneficiary already has been granted a limited power of appointment over the assets of the trust, depending on the state law governing the trust, it may be possible to exercise even a limited power of appointment to cause some or all of the trust’s assets to be subject to transfer tax when the beneficiary dies. To do this, the beneficiary would exercise the original power of appointment in a way that creates a second power of appointment so that second power of appointment can be exercised to prevent the property subject to the power from being owned by someone outright or being transferred for a period of time that does not reference the date upon which the original power of appointment was created.[14] This is colloquially known as “springing the Delaware tax trap.” Nevertheless, the laws of some states prevent the trap from being sprung. Before attempting to spring the Delaware tax trap, consult an attorney in the state whose law governs the trust.
* This hypothetical is for illustrative purposes only. Tax calculations have been simplified for illustrative purposes and do not take into account any tax attributes that may affect a taxpayer's particular situation (for example state and local taxes, marital status, or exemptions).
Table 1: Benefit of Avoiding Estate Tax by Generation*
Trust Not Exempt from Transfer Taxes
Year
1 (Creation)
50
100
150
200
Trust Property
$1,500,000
$10,660,025
$41,666,582
$162,861,163
$636,571,495
Estate/GSTT Tax
($4,797,011)
($18,749,962)
($73,287,524)
($286,457,173)
Balance in Trust
$1,500,000
$5,863,014
$22,916,620
$89,573,640
$350,114,322
Table 2: Benefit of Avoiding Estate Tax by Generation*
Trust Exempt from Transfer Taxes
Year
1 (Creation)
50
100
150
200
Trust Property
$1,500,000
$10,660,025
$75,757,422
$538,384,011
$3,826,124,687
Estate/GSTT Tax
$0
$0
$0
$0
Balance in Trust
$1,500,000
$10,660,025
$75,757,422
$538,384,011
$3,826,124,687
Benefit to Family
$0
$4,797,011
$52,840,802
$448,810,371
$3,476,010,365
A federal estate and/or generation-skipping transfer tax (GSTT). Tax is imposed every 50 years. The federal estate and/or GSTT Tax Rate is 40%. Trust property grows at 4% each year (after federal income tax).
A Flexible, but Complex, Tool
Powers of appointment are powerful planning tools. They can be included in your plan documents at the outset or, depending on applicable state law, added to the terms of an existing irrevocable trust through a modification.
Powers of appointment can be customized to fit your and your family’s particular circumstances. Adding a power of appointment to your plan provides your beneficiaries with the ability to alter the plan to fit changing circumstances.
However, because powers of appointment are powerful, customizable and can have a large impact on taxation, you should consult with your legal, tax and financial advisors when considering adding powers of appointment to a new plan or modifying an old plan to include them.
The annual exclusion amount permits donors to give without facing a gift tax. What should you consider in regards to annual exclusion gifting?
Jun 20 2023 | 3 min read
The federal government imposes a tax on gifts. However, Congress has permitted donors to give a small amount to each beneficiary of their choosing before facing the federal gift tax. This amount is known as the annual exclusion amount, which for 2023 is $17,000 per beneficiary.
The value of all gifts made during the year to a single beneficiary count towards the donor’s $17,000 annual exclusion, no matter what their form. Thus, if you give your child a $10,000 automobile, you have used $10,000 of your annual exclusion and have $7,000 left to give that child within the annual exclusion amount.
Special rules apply to married couples. Two spouses can “split” a gift to a single beneficiary and treat it as if one-half of the total was made by each spouse, no matter which spouse actually made the gift. This technique allows one spouse to make gifts using both spouses’ annual exclusions, for a total gift of $34,000. To qualify for gift splitting, the spouses must file federal gift tax returns signed by both spouses consenting to the split, even if a return would not otherwise be necessary were each to give $17,000 individually.
Your gift must be “complete” by year-end. If making a gift of cash by check close to the end of the calendar year, the check should be cashed before December 31. The gift will not be complete during the time you can stop payment on your check. It is best not to create uncertainty. If making a cash gift right at the end of the year, to avoid any question as to when the gift is complete, consider using a certified check, bank check or, perhaps, a prepaid gift card.
A gift must be of a “present interest in property” to qualify for this exclusion from the gift tax. These are gifts that the beneficiary can access and use immediately.
A gift in trust that benefits the beneficiary only if a trustee makes a distribution from the trust cannot be readily accessed and is not a present interest in property.
Nevertheless, some gifts in trusts can qualify for the annual exclusion, as described below.
· Minor’s Trust under Section 2503(c): Gifts to a minor’s trusts created for a beneficiary under the age of 21 pursuant to Internal Revenue Code §2503(c) will qualify for the annual exclusion. To qualify as a §2503(c) minor’s trust, prior to the beneficiary attaining age 21, distributions may be made only to the beneficiary, the beneficiary must be able to take all property from the trust at age 21, and if the beneficiary dies before attaining age 21, the value of the trust property must be included in the beneficiary’s gross estate either by being paid to the beneficiary’s estate or pursuant to a general power of appointment held by the beneficiary.
· “Crummey” Trust: Gifts to a so-called “Crummey” Trust, that allows the beneficiary (or an adult acting on a minor beneficiary’s behalf) to withdraw a gift to the trust for a limited time after the gift is made, will also qualify for the annual exclusion. Sometimes, depending on the value of the trust, the lapse of the beneficiary’s power to withdraw property from the trust could cause the beneficiary (even if the beneficiary is a minor) to make a taxable gift. Accordingly, care should be used when deciding when and how much of a beneficiary’s withdrawal right should lapse in any one year.
Gifts to grandchildren and more remote descendants could also cause the imposition of a generation-skipping transfer tax (GSTT). This is an additional tax imposed on gifts made to persons two or more generations below the transferor.
Outright gifts to a grandchild or more remote descendant up to the annual exclusion amount are nontaxable gifts and are generally not subject to the GSTT.
Gifts made to a trust for a grandchild do not qualify for this treatment unless the trust is for a grandchild or more remote descendant and during the life of such beneficiary, no portion of the corpus or income of the trust may be distributed to, or for the benefit of, any person other than the beneficiary, and if the trust does not terminate before the beneficiary dies, the assets of such trust will be includable in the beneficiary’s gross estate.
Always remember to consult your attorney and financial advisors when making gifts or creating trusts.
How to get started One hour
Rollover 401k to self directed IRA
Change job how to rollover 401k to your own IRA
Input forms to start your financial plan
Start Financial plan with a CFP Financial Planner Professional
Are your customers raving about you on social media? Share their great stories to help turn potential customers into loyal ones.
Running a holiday sale or weekly special? Definitely promote it here to get customers excited about getting a sweet deal.
Have you opened a new location, redesigned your shop, or added a new product or service? Don't keep it to yourself, let folks know.
Customers have questions, you have answers. Display the most frequently asked questions, so everybody benefits.
Basics Start Estate Plan Documents needed Should I have a will or Trust Privacy concerns
1 Hour Start Financial Plan Live or online
How to allocate security holdings What is my risk tolerance Measure risk of holdings
Having a big sale, on-site celebrity, or other event? Be sure to announce it so everybody knows and gets excited about it.
Are your customers raving about you on social media? Share their great stories to help turn potential customers into loyal ones.
Running a holiday sale or weekly special? Definitely promote it here to get customers excited about getting a sweet deal.
Certified Financial Planner ™Professional CFP r Sylvia Linares-Williams
Rollover 401K or IRA Transfer Get Financial Plan Started
Costs or fees asset management
Classes have no fees
Introductory meeting has no cost
Start a plan in one hour. Rollover 401K or IRA Five things you can do when you change jobs
EVERY 2ND SATURDAY AT 10;30 AM
2420 South Lakemont Avenu Suite 120 Orlando Florida 32814
lIVE OR ONLINE Q
I start by documenting your goals and then compare them to your current portfolio. I use proven investment strategies designed to meet your risk t
Start a plan in one hour. Rollover 401K or IRA Five things you can do when you change jobs
EVERY 2ND SATURDAY AT 10;30 AM
2420 South Lakemont Avenu Suite 120 Orlando Florida 32814
lIVE OR ONLINE Q
I start by documenting your goals and then compare them to your current portfolio. I use proven investment strategies designed to meet your risk tolerance and stand up against market volatility. And you can count on unbiased recommendations and impartial guidance based directly on your needs and goals.
Economics Club Winter Park Florida INVEST IN ORLANDO LOCKHEED MARTIN DISNEY DARDEN SIEMENS AG Consensus earnings estimates Rollover 401K or IRA in one hour I’m passionate about helping both companies and individuals with diversifying portfolios, managing assets, analyzing market trends, and reducing financial risk. My goal? To safeguard t
Economics Club Winter Park Florida INVEST IN ORLANDO LOCKHEED MARTIN DISNEY DARDEN SIEMENS AG Consensus earnings estimates Rollover 401K or IRA in one hour I’m passionate about helping both companies and individuals with diversifying portfolios, managing assets, analyzing market trends, and reducing financial risk. My goal? To safeguard the dreams you strived to achieve and the assets you have worked so hard to accumulate. I use proven investment strategies designed to meet your risk tolerance and hedge against market volatility.
I’m passionate about helping both companies and individuals with diversifying portfolios, managing assets, analyzing market trends, and reducing financial risk. My goal? To safeguard the dreams you strived to achieve and the assets you have worked so hard to accumulate. I use proven investment strategies designed to meet your risk tolerance and hedge against market volatility.
I’m passionate about helping both companies and individuals with diversifying portfolios, managing assets, analyzing market trends, and reducing financial risk. My goal? To safeguard the dreams you strived to achieve and the assets you have worked so hard to accumulate. I use proven investment strategies designed to meet your risk tolerance and hedge against market volatility.
Since 1999, I've been helping business and individuals safeguard their assets and plan for the retirement they want. When I'm not working, I enjoy sailing, cooking, and playing with my 2 dogs.
Tel: 407-405-7579, email startfinancialplan@gmail.com, Bob y Sylvia Williams
Monday - Friday: 9am - 5pm
Second Saturdays each month Start Financial Plan Classes 10:30AM
Sunday:Closed
